Anyone With Experience Partnering With Viking Capital Multi-Family Syndicators
Member since 2023 · 2 posts · 1 vote
Hi,
I am considering investing on a multi-family syndication with Viking Capital. Looks like they have done around 25 syndications worth $800M in property value. Founders are Vikram Raya and Ravi Gupta. If you have had any experience with Viking Capital I would appreciate any feedback on your experience.
Thanks
Don't know anything about them but per my calculations they are taking 27.2% of the capital appreciation on the New Braunfels deal at the end per their projections which seem optimistic in this oversupplied environment, (Austin MSA with largest new multi-family projects coming out this year in the country ,8% of total existing stock and already seeing rent rate declines of near 10%in the city so far) and they are taking a big chunk of the monthly cash on cash as the preferred payouts for their 3 different classes are well below the projected cash on cash total. (They concentrate/force the equity into their class B shares 13/18 million so they get 72% of the future capital appreciation at the higher 30% cut,
versus 5/18mil at the lower 20% rate) They also seem to be overpaying in this downward trending multi-family environment. Also, per their numbers they are buying for 37 mil, debt 24 mil, equity 20 mil, 44mil minus 37 price = 7 million in closing costs, which is 35% of the total equity, RE commissions of say 4% total 1.5 mil so they are taking 5.5 million in fees up front as well minus the inspections/loan fees etc. They appear to be really soaking their unsophisticated investors, my guess they focus on doctors, and it's a risky place and time to be buying too. good luck
That is some great analysis. I would guess 99 out of 100 investors could not have done that research. Great inisght and as the old NBC commercials used to say
"the more you know"

Don't know anything about them but per my calculations they are taking 27.2% of the capital appreciation on the New Braunfels deal at the end per their projections which seem optimistic in this oversupplied environment, (Austin MSA with largest new multi-family projects coming out this year in the country ,8% of total existing stock and already seeing rent rate declines of near 10%in the city so far) and they are taking a big chunk of the monthly cash on cash as the preferred payouts for their 3 different classes are well below the projected cash on cash total. (They concentrate/force the equity into their class B shares 13/18 million so they get 72% of the future capital appreciation at the higher 30% cut,
versus 5/18mil at the lower 20% rate) They also seem to be overpaying in this downward trending multi-family environment. Also, per their numbers they are buying for 37 mil, debt 24 mil, equity 20 mil, 44mil minus 37 price = 7 million in closing costs, which is 35% of the total equity, RE commissions of say 4% total 1.5 mil so they are taking 5.5 million in fees up front as well minus the inspections/loan fees etc. They appear to be really soaking their unsophisticated investors, my guess they focus on doctors, and it's a risky place and time to be buying too. good luck
Wow, Amazing @Paul Azad. I was thinking about investing in the Austin deal. Excellent Analysis.
Don't know anything about them but per my calculations they are taking 27.2% of the capital appreciation on the New Braunfels deal at the end per their projections which seem optimistic in this oversupplied environment, (Austin MSA with largest new multi-family projects coming out this year in the country ,8% of total existing stock and already seeing rent rate declines of near 10%in the city so far) and they are taking a big chunk of the monthly cash on cash as the preferred payouts for their 3 different classes are well below the projected cash on cash total. (They concentrate/force the equity into their class B shares 13/18 million so they get 72% of the future capital appreciation at the higher 30% cut,
versus 5/18mil at the lower 20% rate) They also seem to be overpaying in this downward trending multi-family environment. Also, per their numbers they are buying for 37 mil, debt 24 mil, equity 20 mil, 44mil minus 37 price = 7 million in closing costs, which is 35% of the total equity, RE commissions of say 4% total 1.5 mil so they are taking 5.5 million in fees up front as well minus the inspections/loan fees etc. They appear to be really soaking their unsophisticated investors, my guess they focus on doctors, and it's a risky place and time to be buying too. good luck
I have invested in their 2 deals. So far receiving all my preferred returns. Keeping my fingers crossed.
Don't know anything about them but per my calculations they are taking 27.2% of the capital appreciation on the New Braunfels deal at the end per their projections which seem optimistic in this oversupplied environment, (Austin MSA with largest new multi-family projects coming out this year in the country ,8% of total existing stock and already seeing rent rate declines of near 10%in the city so far) and they are taking a big chunk of the monthly cash on cash as the preferred payouts for their 3 different classes are well below the projected cash on cash total. (They concentrate/force the equity into their class B shares 13/18 million so they get 72% of the future capital appreciation at the higher 30% cut,
versus 5/18mil at the lower 20% rate) They also seem to be overpaying in this downward trending multi-family environment. Also, per their numbers they are buying for 37 mil, debt 24 mil, equity 20 mil, 44mil minus 37 price = 7 million in closing costs, which is 35% of the total equity, RE commissions of say 4% total 1.5 mil so they are taking 5.5 million in fees up front as well minus the inspections/loan fees etc. They appear to be really soaking their unsophisticated investors, my guess they focus on doctors, and it's a risky place and time to be buying too. good luck
Why in the world people want to invest in Austin at this time is beyond me ….
This is the lowest rent growth and massive oversupply ….
Even if one is trying to invest at MF , invest in lower supply market like New Jersey
how is it possible increasing rent 50% in 5 years period in place where comps and rent is decreasing, this local market is extremely saturated.
For me if I have to buy in Austin I would find complex that could give DSCR 1.3 at least with 80% occupancy.
if they increase rent 50% then we should do intelligence on their closest neighborhood's rent.
On expensive apartment like these, if rent is too high, they would just rent a single family. lol.
too much work for nothing.
I should have been more specific as everyone was jumping to Austin Texas. I was looking at the Dawson Creek offering in Atlanta GA. I ended up not investing for a few reasons even though the syndication sounded interesting:
- They said they were oversubscribed but would still accept some additional funds. Did not seem that interested in my money.
- I had a call a 1X1 call with them that was helpful. They provided me a sign in to their data mart with more details. It had nothing other than a high-level presentation like they had on their website.
- They promised to send me more details on the offering and never sent me anything. If they had oversubscribed and wanted to accept more funds, they should have followed through.
Bottom line - I never followed up again. If they directed me to a site that had no new information and they never followed up with additional information; it was a red flag for me. Why would I want to invest when this level of transparency was poor at the outset.
the best way to do DD is to do intel gathering on their comps, if their peer is renting 2BR for $2K how could they expect to rent it for $3K on year 5. Is it even making sense ? What's the DSCR assumption with 92% occupancy, with no rent growth, with rent growth , and lot of other thing. Can they provide you their T-12 ? How could they raise their price if their competitor is increasing lol
many times, the syndicator exist because they get paid for free by LP. THey get reap all the benefits while if investment doesn't return any value, they would not lose money, but LP is the one that's taking risk.
Hi Carlos, they had a webinar 2 days ago, the youtube below, they put in a table of other comparable Apartment complexes even with a map, showing the proximity as well. I suppose to show the Sundance Villas slightly lower avg rents but on the list of 10 complexes are 2 brand new massive complexes with 0% occupancy which are coming online soon. They didn't mention them nor the high likelihood of that competition driving down their rents and thus Noi and cap rates etc. which I think is an obvious detriment to their slightly Rosy projections. It's going to be tough for Multi-family investing just now in Hot Markets, may be prudent to limit investing until things shake out a bit over next 12 months....I think triple Net retail has better wind at its back from supply/demand basis at this time. Warren buffet used to say why jump over 1 foot hurdles when you can jump over 1 inch hurdles?
Don't Miss Out: Villas at Sundance New Investment Offering Webinar (youtube.com)
sorry forgot to add this table from Yardi-Matrix , shows the major MF rental markets, Austin is worst with 5.9% drop in rents and 5% new units,
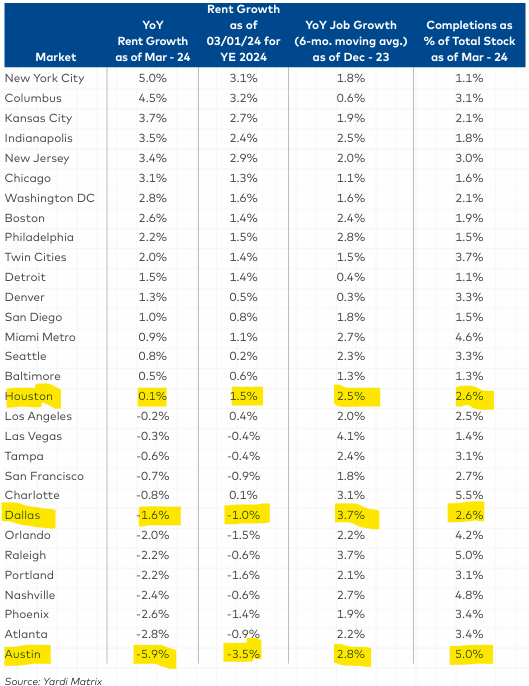
today's vacancy rate...... at least if one want to really desperate to invest ,look at Baltimore for example.

Viking is offering a Hyro GP Fund which I am seriously considering. Any thoughts on this?
@Aileen Ciocon is it this? https://vikingcapllc.com/listen-watch/hyrowebinar/
I do not have commentary on this offering, per se, but rather for any pref equity fund investment:
What are the terms the underlying GP is signing off on, that allows Viking to offer you, the LP, an 11%+ return, net of all fees and carried interest?
How is Viking controlling how the capital is being used? Are there any specific situations that the always veto? I.e. if the money is used to extend a rate cap for 1 yr, I could see that being a major red flag.
What type of voting rights is Viking requiring? Can they force a sale of the asset and/or any other asset the underlying GP as pledged as collateral?
Are the underlying GPs signing personal guarantees for the money? What type of credit checks/liability checks are Viking performing on those underlying GPs?
Ultimately, I am always a bit skeptical of these pref equity investments. They all feel like they are catching a falling knife. A great asset with low leverage and plenty of cash flow is not in need of pref equity. So, even though there is protection in being right behind the debt, there is risk in the basic fact that the underlying GP needs rescue capital in the first place.