Applying For A Loan (VA Loan)

Applying For A Loan (VA Loan)

Richmond, RI · Member since 2019 · 124 posts · 40 votes

Hello Everyone,

I recently applied for a VA Loan through a mortgage banker. After the mortgage banker pulled my credit history, I was told that I "don't have any credit history, and therefore no credit score".

The mortgage banker said that I should open couple of tradelines, and that it will take 6 months for the credit bureaus to report credit scores from the day the creditors start reporting. It was recommended that I go to Citi Cards and Discovery and apply for a $200 secured credit card, (and possibly apply for Costco after doing this). I was also told to never go over 50% balance, otherwise I would receive a low score.

I don't feel comfortable doing this, because I do not feel this to be sound advice. I have a credit history because I took out a consumer loan, and I also did an auto loan. I paid everything on time, never defaulting, going up to 2014. I have not done anything since 2014 that would lower or raise my credit score. I have some questions to share: 

1.  The assumption is that the credit score that I had from 2014 fell to zero since I have no recent credit history. Although I may have not have done anything from the past 6 months or so, do the major credit bureaus suddenly drop my score to zero? Can anyone provide direction as to where exactly I can find out what the credit bureaus actually do with one's credit score in a situation like this?

2. Can one still have a credit score, although with no recent credit history? I would assume so, but I truly do not know. This pretty much ties in with #1. 

3. I received an email from Experian saying to review my credit report and my FICO score. I received this email on the same day that the mortgage banker made the inquiry on my credit history. If I do not have a credit score due to having no recent credit history (no score shown on the pulled report), then why would Experian send an email telling me to review my credit report along with my FICO score? 

4. In the near future, I plan to apply for a consumer loan, and use some of it for opening an index fund and for opening an SDIRA account. If I were to be approved for the loan and I start paying it off (on time), wouldn't this suffice for raising my credit score? 

5. If the situation above were to happen, would I have to wait for 6 months, or would I be able to receive a credit score before then?

I feel that opening tradelines and applying for credit cards does not align with with what I am trying to accomplish, can anyone provide any recommendations?

V/R,

Chauncy


0Reply
10 views

Most Popular Reply

Guy with Great Hair · Austin, TX · Member since 2013 · 2k+ posts · 4k+ votes
7y

1. after 7 years everything will drop off your report if it's inactive. Never heard of it in 5 years, but definitely possible, especially if you have a light record

2. Not really, credit score is a summary of the history. The history matters way more, but underwriting guidelines are going to give you terms based on the score. 

3. seems you must have some kind of account with experien that they have your email address. they have a record of your credit being pulled and sent you a notification. This is very standard. 

4. you're going to take out a uncollateralized loan from a bank and then invest it in an IRA? this is a terrible idea, and the issuing bank isn't going to like that at all.

5. the 6 month requirement is not how long it takes to get a score, you'll get a score right away. The bank is going to want more than 1-2 months of payment history to judge your credit worthiness, the longer the better

So my advice is to A. start using credit karma immediately. it's free and accurate enough and B. if you want to use banks and debt to run your investment strategy, then you need to participate by their rules. If you don't want to carry any open debt, then the few times you want some it'll always be this hassle. Keep some open credit cards at all times even with low or zero balances, every bit helps. You will need to get some tradelines with a good credit history if you want to prove to a bank that you're a worthy credit borrower. There are many ways to do this, but a few small credit cards is the easiest way. The fastest way would be to go finance a BMW, but that's a worse recommendation LOL 

See this reply in the discussion

6 Replies

Jump to latestLatest
  • Guy with Great Hair · Austin, TX · Member since 2013 · 2k+ posts · 4k+ votes
    7y

    1. after 7 years everything will drop off your report if it's inactive. Never heard of it in 5 years, but definitely possible, especially if you have a light record

    2. Not really, credit score is a summary of the history. The history matters way more, but underwriting guidelines are going to give you terms based on the score. 

    3. seems you must have some kind of account with experien that they have your email address. they have a record of your credit being pulled and sent you a notification. This is very standard. 

    4. you're going to take out a uncollateralized loan from a bank and then invest it in an IRA? this is a terrible idea, and the issuing bank isn't going to like that at all.

    5. the 6 month requirement is not how long it takes to get a score, you'll get a score right away. The bank is going to want more than 1-2 months of payment history to judge your credit worthiness, the longer the better

    So my advice is to A. start using credit karma immediately. it's free and accurate enough and B. if you want to use banks and debt to run your investment strategy, then you need to participate by their rules. If you don't want to carry any open debt, then the few times you want some it'll always be this hassle. Keep some open credit cards at all times even with low or zero balances, every bit helps. You will need to get some tradelines with a good credit history if you want to prove to a bank that you're a worthy credit borrower. There are many ways to do this, but a few small credit cards is the easiest way. The fastest way would be to go finance a BMW, but that's a worse recommendation LOL 

  • Richmond, RI · Member since 2019 · 124 posts · 40 votes
    7y

    Hello Alexander,

    I pass on the BMW, haha. 

    Thank-you for shedding some light on some things, I appreciate it. 

    I have used Credit Karma once before, so I will keep it as a source of reference. I do have an account with Experian, so I receive emails from the bureau every now and then. 

    I have learned as to how much an investor has access to, for simply  maintaining a good/great credit history, by using the tradelines and credit cards. I will do more research and see as to what the best options are. 

    Back in college, I took out a consumer loan and used a portion of it for opening a Roth IRA account. The military institution I was in provided the opportunity for students to take out a loan from its associated bank, Navy Federal. It was a great deal, the interest rate was only 0.5%. It was easy back then, because everyone paid off their loan balance through military service.

    Of course, that was back then, things are different now, as I am out of the service. I know how much I want to use (around 16.67% of the loan), but I want to at to at least get an idea as to what I can do. The worst the bank can say is no (with a slight drop in my credit score I suppose).

    V/R,

    Chauncy

  • Springfield, VA · Member since 2019 · 74 posts · 77 votes
    7y

    You might want to check into a mortgage lender that can do manual underwriting. Here's a basic primer that helped me understand it:

    https://firstquarterfinance.co...

  • Richmond, RI · Member since 2019 · 124 posts · 40 votes
    7y

    Hello Mac,

    I just wanted to say thank-you so much for sharing this with me! I had no idea about manual underwriting. I had no idea that my bank does manual underwriting for loans, including the VA loans. I've only seen the bank advertise its promotions and credit card offers, lol.

    V/R,

    Chauncy

  • Rental Property Investor · Raleigh, NC · Member since 2016 · 393 posts · 995 votes
    7y

    @Chauncy Gray Advice from a fellow vet.  Get a credit card.  They are the biggest financial military secret that nobody talks about.

    Credit cards get a bad rap, and in some cases rightfully so.  In the wrong hands a credit card can financially ruin someone for the next decade by overspending and then getting stuck with astronomical interest rates.

    However in the right hands, a credit card is a wonderful invention.  Remember you only pay interest if you carry a balance from statement to statement, so in my nearly 20 years of owning a credit card, not once have I ever paid any money to my card companies.  I do however get large amounts of promotional freebies and cashback from them.  Think about that for a moment, my credit card companies pay me, not the other way around.

    Secondly, credit cards for currently serving military members are so astronomically amazing that I'm surprised the credit companies haven't changed their own rules.  I currently have several cards that combine to offer me roughly $3000 worth of free travel every single year that I can either use immediately, or stockpile it for my big world tour once I retire.  

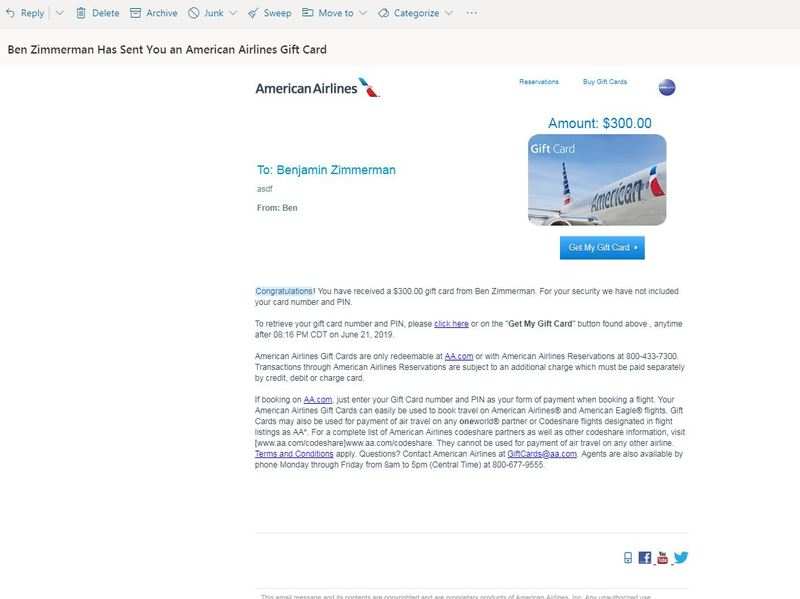
    I'm NOT talking about airline cards that give you 1 mile for every dollar spent, or even talking about the sign up bonuses, many of these card's I have never once used... EVER... and yet they give me these benefits simply for having the account open.  I've been doing this for a few years now and currently have roughly $12,000 worth of virtual airline gift cards sitting in my email box waiting to be used and I didn't need to ever make a single swipe of the card to get this.  

    If your interested in learning how this is done, feel free to PM me.

  • Richmond, RI · Member since 2019 · 124 posts · 40 votes
    7y

    @Ben Zimmerman, I appreciate your advice. Thank-you!

Join the conversationCreate a free account to reply, vote on answers and follow this thread.