Lump Sum Whole Life Insurance vs. Simply Invest

Lump Sum Whole Life Insurance vs. Simply Invest

Member since 2019 · 24 posts · 12 votes

All - there is some great information on here regarding utilizing a maximum overfunded whole life insurance policy to then take a loan out and invest in rental properties. One question I can't seem to answer or grasp onto is if you can open a policy with a lump sum? 

I'll give you context, I am taking about $30k equity from my personal residence. I'd like to utilize that to buy investment properties. It sounds like a benefit could be opening a whole life insurance policy to "triple play" the situation but is it possible to open a policy with a "lump sum" rather than a premium (or maybe in addition to premium.) 

What would my options be or would it be better if I just invested "normally" for now and keep the insurance policy in mind for when I have more cash flow coming in? 

Any advice from those who are knowledgable and have used the whole term policy is greatly appreciated!

Eric
0Reply
103 views

Most Popular Reply

Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
6y

@Eric Lunsford

Don't do it. The quick explanation is that the death benefit is a function of the first year premium. The policy issue charge is a function of the death benefit. The policy issue charge is assessed annually during the surrender charge period of your policy. 

So by dropping in a lump sum instead of spreading it over 5 years, you will have a death benefit that is 5X higher. The costs will also be 5X higher and will continue long after the premium is paid. This consumes a lot of the extra cash value that you had at the beginning.

If you have a lump sum, the optimal funding period is 5 years. That keeps the fees to a minimum while allowing your cash to go to work as soon as possible. You could do 10 years and keep the costs down even more, but you'll have less cash value because you missed out on the compounding interest in the early years.

See this reply in the discussion

13 Replies

Jump to latestLatest
  • Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
    6y

    @Eric Lunsford

    Don't do it. The quick explanation is that the death benefit is a function of the first year premium. The policy issue charge is a function of the death benefit. The policy issue charge is assessed annually during the surrender charge period of your policy. 

    So by dropping in a lump sum instead of spreading it over 5 years, you will have a death benefit that is 5X higher. The costs will also be 5X higher and will continue long after the premium is paid. This consumes a lot of the extra cash value that you had at the beginning.

    If you have a lump sum, the optimal funding period is 5 years. That keeps the fees to a minimum while allowing your cash to go to work as soon as possible. You could do 10 years and keep the costs down even more, but you'll have less cash value because you missed out on the compounding interest in the early years.

  • Member since 2019 · 24 posts · 12 votes
    6y

    @Thomas Rutkowski your site and resources are exactly what got me into looking into whole life and making this post. :) I appreciate the value you add! 

  • Member since 2019 · 24 posts · 12 votes
    6y

    @Thomas Rutkowski I watched your video you recommended. Very good explanation - I was (obviously) completely unaware that the first year is a big determining factor. A couple of clarifying questions if you don't mind: 

    1. You mentioned spreading the $30k over a 5 year period. So essentially designing a plan at $6k a year for the first 5 years? I'd still plan on investing my $30k now on real estate but maybe fund that plan with the cash flow from investment property now? 

    2. You also mentioned doing a face reduction after the first 5 years. I assume this essentially "refinancing" in a way? Renewing your premium agreement? 

    3. Lastly, you mentioned getting as small base policy as possible. What does this mean exactly? Is it reasonable (maybe even beneficial?) at this time to purchase a policy where I simply put my cash flow from REI into the policy? As that number grows, would I be allowed to put more than the premium in?

    Thank you again for the wealth of knowledge. I'm simply trying to figure out how to eventually be my own banker in order to get loans for REI. Running the numbers, I can see how my DTI in REI will quickly get to a point where banks will not want to lend. Yes, there's private money but it's always good to have multiple sources.

  • Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
    6y

    @Eric Lunsford

    1. The real problem is liquidity. If you do a 5-pay design with $6K/yr for 5 years, you'll start with approximately $4,800 of cash value in your policy plus the remaining $24,000 that isn't in the policy. $28,800 that can be invested. Depending upon what you invest in, you may have trouble getting the $6K out each year to pay the premiums.

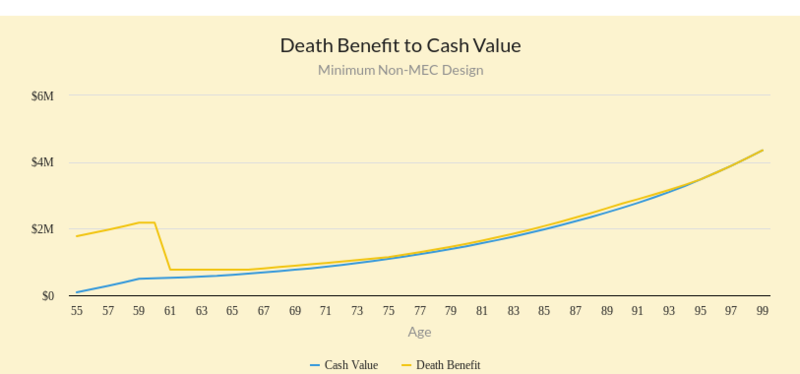
    2. Its all about driving the cost out of the policy, not refinancing. If you graph the death benefit and cash value in a 5-pay design, it looks like this...

    If you think of the death benefit as the primary cost driver in a policy, you can see that from year 6 onward, there is very little cost in the policy. The expense ratio after Year 10 is ~0.25%... very low. This one has a very large premium and death benefit, but its all scaleable.

  • Member since 2019 · 24 posts · 12 votes
    6y

    Thanks @Thomas Rutkowski! I imagine that by year 2 I will likely have at least 2-3 properties that cash flow at least $350/mo so the $6k/year premium isn't completely out of the picture. 

    I have a little "bad" debt that I'd like to use that cash flow to pay off but then I imagine what I'll do is save the the cash flow to reinvest. Instead of simply saving in my bank account, it seems whole life insurance could be a solution. 

  • Member since 2019 · 24 posts · 12 votes
    6y

    @Thomas Rutkowski - another question if you don't mind. If you were to set up a plan where you're putting, say, $5,000 a year into premiums, do you have the option to put more I ask because my cash flow will likely go up throughout the year and I'd like to use it as a "savings" account and just put any profit into the plan. Is that possible? Does that benefit the growth of the plan per CV? 

  • Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
    6y

    @Eric Lunsford

    With a Universal life policy, the death benefit and premium can be changed at any time. When you find yourself wanting to increase the premium, all you need to do is increase the death benefit on the policy just enough to allow the new premium into the policy. If done right, the policy will still have the minimum possible death benefit for the premium.

    Whole Life doesn't offer the flexibility to increase premiums. If you knew the schedule of premium increases in advance, I might be able to design something that works, but most people don't have the luxury of knowing when they'll have more money.

  • Member since 2019 · 24 posts · 12 votes
    6y

    @Thomas Rutkowski

    Thank you. I'm not interested in ULI at this time based on the research I've done so far, but I might dig into it a bit more as I would love to continue to put my cash flow from properties into the plan. What makes that challenging though is I predict my cash flow will double each year at least. It would have been easy if it were an option to just continue using the Whole life plan as a savings account. 

    As you mentioned, if I took the 30k I currently have and did a 5 pay design I would need to essentially put $6k a year in as premium. I believe I would be able to do that with my cash flow for the first year but theoretically at year 2 I would be able to put that plus a significant amount more in (and more in year 3 and so on). I'm not too interested in the death benefit but would love to take advantage of getting more and more CV from the plan in an effort to ultimately fund my real estate deals. 

  • Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
    6y

    @Eric Lunsford

    Most everything you've ever heard about IUL are myths perpetrated by people who sell IUL. Either type of policy works for this, but if you truly want the best performing private bank, an IUL is going to outperform a similarly designed whole life. 

  • Member since 2019 · 24 posts · 12 votes
    6y

    @Thomas Rutkowski

    I have another question for you that may be a bit more of an opinion, but I thought I'd post anyway as there may be some others in the future with a similar question. First of all, one thing that wasn't clicking for me earlier which caused my last post about adding income is that as income grows you can always get another policy, correct? Is there a limit to how many different whole life ins policies one person has? 

    My primary question thought was surrounding debt - still wrapping my head around this infinite banking concept. I have about $17k of consumer debt I'm working on getting rid of. I pay about $750/mo more than the minimum payments in a snowball method. Is there any value, that you see, in putting that money (about $8400/year) toward a whole life policy and then when the cash value equals or exceeds my debt amount in the next couple of years, borrowing against my policy to pay the debt off? All of this compared to simply just paying the 700 directly to debt? 

    I see the benefit as my money is growing while I have a policy and while I'm repaying the loan to my policy. But I'm not sure all of that is worth it as I'm waiting a couple of years at least just to have enough CV to take a loan out. 

    Any advice or input is appreciated. 

  • Financial Advisor · Boynton Beach, FL · Member since 2015 · 834 posts · 798 votes
    6y
    Originally posted by @Eric Lunsford:

    @Thomas Rutkowski

    I have another question for you that may be a bit more of an opinion, but I thought I'd post anyway as there may be some others in the future with a similar question. First of all, one thing that wasn't clicking for me earlier which caused my last post about adding income is that as income grows you can always get another policy, correct? Is there a limit to how many different whole life ins policies one person has? 

    My primary question thought was surrounding debt - still wrapping my head around this infinite banking concept. I have about $17k of consumer debt I'm working on getting rid of. I pay about $750/mo more than the minimum payments in a snowball method. Is there any value, that you see, in putting that money (about $8400/year) toward a whole life policy and then when the cash value equals or exceeds my debt amount in the next couple of years, borrowing against my policy to pay the debt off? All of this compared to simply just paying the 700 directly to debt? 

    I see the benefit as my money is growing while I have a policy and while I'm repaying the loan to my policy. But I'm not sure all of that is worth it as I'm waiting a couple of years at least just to have enough CV to take a loan out. 

    Any advice or input is appreciated. 

    Yes, you can have multiple policies. With an IUL/UL, you can modify the existing policy as your income changes or start a new one if you want to add coverage for a spouse or children.

    You can create a very simple tax arbitrage by swapping out the high interest credit card debt with low interest policy loan debt. Once that is done, then you can start to displace the loans and free up the cash value. I've built a financial model that shows that this is more effective at building wealth than by paying off the debt and then investing. Its pretty obvious when you realize that the money simply has more time to work.

    Hope this quick answer helps.

  • Rental Property Investor · Honolulu, HAWAII (HI) · Member since 2011 · 4k+ posts · 2k+ votes
    6y

    If your networth is under 500k you need to just invest. IBC or wholelife will have fees and you need every penny going to assets.

  • Investor · Broward County, FL · Member since 2018 · 1k+ posts · 938 votes
    6y

    @Lane Kawaoka

    The fee is a small percentage of what you put in the policy. The fixed costs are very minimal. So it does not matter how much is your net worth. You can get a $5000/year policy or a $100,000 policy and the cost will be almost the same ratio on both.

    The only issue is that it is easier to find $100,000 high yield investments than $5,000 ones.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.