My lender didn’t rate lock on time and rates went up

My lender didn’t rate lock on time and rates went up

Member since 2021 · 20 posts · 0 votes

Hi guys. Can any actions be taken against the mortgage broker for not locking in my rate when the rate was still low? We have been trying to refi since November. We are in March and we have submitted everything they asked for and have been doing everything they asked for. The broker sent us the loan commitment letter to sign but the language in there indicated it was "variable" - I of course questioned that but it took him (no joke) 3 weeks to answer the question of if it's in fact variable or fixed. When he confirmed, we asked him for a new loan commitment letter without any wording of variable and then we were waiting and waiting. Long story short, he apologized for dropping the ball and missing the time to lock our rate when it was still low. Now rates are higher and he is asking that we bring more money to the closing to lower LTV. We were already bringing more than we originally discussed. I'm disappointed and at this point financially drained becuase we have to maintain our crazy mortgage and we had to pay off some debt under his request. Is there anything I can do? He did say that he will try to close us at the lower rate and will loose our commission but then he said he will do that and we would have to bring more money to closing table. It's been almost 2 days and we still don't know how much money. Any advice would be greatly appreciated!! Thank you!!

0Reply
366 views

Most Popular Reply

Russell BrazilBusiness Member
Moderator
Real Estate Agent · Washington, D.C. · Member since 2012 · 17k+ posts · 30k+ votes
5y

Where did you find the lender? #whoyouworkwithmatters. Not all real estate professionals are created equally. Many people have their balls dropped while shopping for things like the cheapest rate instead of working with a quality professional. Always ends up costing more in the long run as we see this story as an example. 

See this reply in the discussion

36 Replies

Jump to latestLatest
  • Investor · San Diego, CA · Member since 2016 · 265 posts · 305 votes
    5y

    @Evelina Khaimova

    Sorry to hear. That is frustrating.

    I had a similar scenario about a year ago where the lender did not close in time and told me the rate lock had expired. The new rate 30 days later was now higher than at time of origination. I was able to use emails to stitch together a timeline and show the lender that I had always answered any questions or provided documentation with 24 hours of the request. So, long story short....I proved that they were not able to meet their own timeline. They honored the original rate lock and we closed within a couple weeks.

    As others have said, I would have cut loose this lender and moved on after a week or two if no response. Any good professional should have an auto reply if they are truly not available for business for an extended period of time.

    Document all Q&A, anticipated dates, etc in email even as a follow up to a phone call.

    Pay for the extended rate lock. If they offer 30 day lock or 45 day lock. Choose 45 day lock. Several lenders are offering 60+ lock periods right now. It may only be an extra $100 to extend your lock period for 15-30 days.

    Negotiate appraisal waivers regardless of good or bad performance by the lender.

    If points are high for the rate you want, maybe negotiate a reduced origination fee.

    Also, if you are buying (vs refi), you can often negotiate for the seller to pay closing costs. Simply add the closing costs to the closing offer. Instead of paying up front cash to close, the closing costs will essentially be financed meaning you may only be paying 20% of the closing costs with the 20% down payment or similar.

  • Member since 2021 · 20 posts · 0 votes
    5y

    @Eric Schultz thank you. We are refinancing. He sent me back the new paper itemizing where every dollar is being spent but I didn’t see the “origination” fee - would it be under another name? Also - he is giving us the 2.875% BUT we are now paying $8K in points to get there. So instead of bringing $1200 to closing like we agreed, we have to bring $15K to closing to get the rate we want. However the loan isn’t getting smaller. The loan amount is still the same number as it was when we were brining $1200 to closing. Mind you, he also made us pay off $9K in CC debt. We had to do a forbearance last year when corona lockdown started and then in 6 months we did deferral. We started paying more for the mortgage monthly ($700 a month more) ... we did all he asked of us, blah blah... in the end - to do this refi we are going from 4.5% at $540K Appx in loan to 2.875% with a loan that’s $30K more!! Mind you, all the extras we had already paid and all the extra we will end up paying. This mistake of not closing rate on time is now beginning to cost me and I am beginning to think that even though he is saying he will waive his commissions and do this loan for free that maybe he isn’t doing loan for free and those commissions would end up being tucked into some sort of fee we could of get reduced too. I’m not even sure how to approach all this 

  • Member since 2021 · 20 posts · 0 votes
    5y

    @Philip Garcia - I have emails and texts showing everything. His latest email said that he will give me the 2.875% but it will be with points. He also said that he will loose his commissions on this but the bank will not do any lender credits as the bank will not come out of pocket for anything. I haven’t replied yet. How would you reply to this? 

  • Member since 2021 · 20 posts · 0 votes
    5y

    @Crystal S. thank you for your response. I see you are in NJ. I am in NY. The lender is now charging us $8K in points to get to the 2.875% ... He said that he will do this loan for free but the bank will not be coming out of pocket in lender credits. Weeks ago he send me the loan commitment to sign on a Friday mid day. I reviewed everything and there was verbiage there saying the rate would be variable. I called, then emailed then texted asking him to clear this up for me and resend the new loan commitment letter immediately. For 3 WEEKS we couldn’t get the response as to why there was a “variable” language in the LC letter. Finally i got fed up and my husband got involved - he told my husband over the phone that he dropped the ball and forgot to rate lock us when the rate was at 2.875%. He apologized and said that even if he has to do the loan for free, he will do it. What we didn’t know was all the fees that he would charge us to get to that 2.875%. I’m appalled as to what is going on and honestly feel so helpless at this point. Our mortgage is creeping up becuase of the loan defferment due to corona and we are also paying $700 more a month on a mortgage that isn’t even getting applied to our principle. The loan is going up, we cannot close.. he made us pay off $9K in credit cards, now he is asking for $15K at closing as opposed to $8K that we agreed to originally. He said we should dip into our retirement since he knows we don’t have the extra money to do this. Why do I need to dip into retirement when I wasn’t the one who made this mistake. I don’t know how to approach this. 

  • Member since 2021 · 20 posts · 0 votes
    5y

    @Eric Schultz my apologizes, it was $8K that we had to bring to closing which we agreed on. Now it’s $15K to bring to closing... which $8K is now applied towards discount points. 

  • Investor · San Diego, CA · Member since 2016 · 265 posts · 305 votes
    5y

    @Evelina Khaimova

    The lender’s commissions are usually under “guaranteed lender fee”, “origination fee” or they are likely charging you more points to hide the lender fee.

    Look for a Lender Credits line item on your preliminary Closing Statement. If you don’t see it, ask for where the Lender Credit is to reduce your cash to close amount.

    The lending environment has definitely changed since March 2020. You could always get another rate quote and decide if you want to close on this loan or not with this particular lender. You can always walk away before doc signing...

    Here are the steps to determine where you are at in the loan process:

    Step 1: Apply for Loan.

    Step 2: Loan Officer Review.

    Step 3: Initial Processing.

    Step 4: Initial Underwriting.

    Step 5: Final Processing.

    Step 6: Final Underwriting.

    Step 7: Closing Disclosure.

    Step 8: Doc Drawing.

    Step 9: Doc Signing.

    Step 10: Closing.

  • Stephanie MedellinBusiness Member
    Mortgage Broker · CA · Member since 2014 · 1k+ posts · 644 votes
    5y

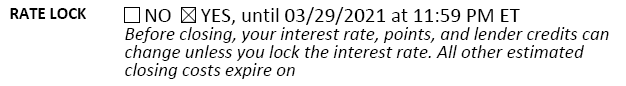
    @Evelina Khaimova  When you receive a loan estimate, in the top right corner it will indicate whether the interest rate is locked, and if locked, the date when the lock will expire.  The lender has 3 days to send you an updated loan estimate after locking your rate.  If you have not received an updated loan estimate, you can assume your rate has not been locked.

    Stephanie Medellin, Loan Factory58 Reviews
  • Lender · NJ · Member since 2016 · 41 posts · 14 votes
    5y

    @Evelina Khaimova

    Hi Evelina,

    I apologize for the delayed response.

    I would absolutely not do the loan with these people.

    I would go somewhere else.

    I have done NY loans the only difference is the mortgage tax and having to go through the CEMA to lower the mortgage tax, this process takes 4-12 weeks. Are you guys doing a CEMA?

    I have never charged points unless it was at the borrowers request because they wanted lower rate then originally given!

    Rates have gone up now but they are still record low.

    I would definitely drop this guy!

    If your not doing a CEMA your refi should only take 30 days.

    I would not take anything out of your retirement.

    There is no need to this lender is just being greedy because he knows what you do not and that’s not right! Now you feel backed into a wall!

    Walk away!

    Sorry your having to go through this!

    This makes me so upset that other lenders are doing these things!

    Warm regards,

    Crystal

  • Rental Property Investor · Boston, Massachusetts (MA) · Member since 2016 · 2k+ posts · 2k+ votes
    5y

    @Evelina Khaimova while this guy doesn't necessarily sound like gods gift to mortgage brokers I think you should look at a few things in the spirit of getting your own house in order:

    1) your debt to income ratio didn't qualify you...he worked with you anyway and you paid off the credit cards. And he offered up the only thing under his control, his commission.

    2) you didn't have very much in liquid funds outside of your retirement account (nothing wrong with that, I've used mine too) 

    3) you were in FORBEARANCE and DEFERRAL (???!!!) and you expect an easy time of this? And a 2.75% rate??? This may offend but you are lucky to have anyone loan you money right now. 

    4) You are a high risk client and your loan qualifications are being treated accordingly

  • Lender · NJ · Member since 2016 · 41 posts · 14 votes
    5y

    @Evelina Khaimova

    You can send a complaint about him to NMLS as well as the CFPB and also the NY banking board.

    Also write a bad review about him if he’s on google and Zillow as well...

    Hope this helps!

    Crystal

  • Member since 2021 · 20 posts · 0 votes
    3y
    Quote from @Crystal S.:

    @Evelina Khaimova

    Hi Evelina,

    I’m sorry this happened to you, generally if the lender dropped the ball they should be giving you some lender credits to make up for their fault!

    I personally would not deal with them!

    What rate did he give you now? Is it fixed? Also I would read your closing disclosure to see if he is already charging points that your unaware of!

    I have refinanced loans to where a client was with another lender and they had no idea that that lender was charging them $8,000 in points!

    Make sure your reading your closing disclosure throughly.

    Also there is a 3 day rescission period which means even if you do sign you still have 3 days to back out of the loan after signing.

    Regards,

    Crystal

    @Crystal S.

    @Crystal S. This is SO overdue!!! But thank you for being able to get us all refinanced at the time!!! You really held our hand through the entire process and made the refi happen for us!!! You saved us a lot of money!!! Thank you!!! 

Join the conversationCreate a free account to reply, vote on answers and follow this thread.