HELP!! Bought 2nd mortgage on Judicial sale in Illinois, Cook ct

HELP!! Bought 2nd mortgage on Judicial sale in Illinois, Cook ct

Member since 2019 · 10 posts · 2 votes

So I thought I was buying the 1st mortgage here's what happened.

2nd Mrg 200K in 2009 - harris bank
1st Mrg 100K in 2007 - harris bank - this is the one that is being foreclosed, but it also has a subordination file.

The judicial sale happened in Aug 2019, the opening bid was around 100K ish and I bought it for 140K ish, so the surplus is 30K.

Questions:
1. Did I buy this as a second mortgage or 1st?
2. Even though it was registered/filed in 2007 is it considered as first or second mrg?
2. The property is worth around 450K as is and if remodeled 700K.
3. What rights do I have, can I pay off the mortgage that was in 2009 and get the property?
4. What should I do?

Side notes:
a. Property is occupied and I spoke with the owner 1 week after winning and told him we want to do a cash for keys, but he was shocked that his house sold and told me that he was still making payments monthly, (I assume now that he was making payments on 200K mrg in 2009.)
b. In September the court approval supposed to happen but the owner hired a lawyer stating that he never got any notice of sale which I dought and so the hearing is next in mid-October.

P.S - I did hire a lawyer to look over the properties I bid on, but i feel like he doesn't know his stuff.

Here's the subordination:

0Reply
143 views

Most Popular Reply

Real Estate Professional · West Palm Beach, FL · Member since 2012 · 23k+ posts · 13k+ votes
7y

@Ron S. It Was the second mtg holder (former first mtg, but subordinated their mtg) that foreclosed.  Since the remaining mtg is Superior to the foreclosing mtg holder, I don’t see them getting any surplus....they wouldn’t in FL, since their mtg stays intact.

An interesting quirk in our foreclosure laws here....when an hoa forecloses, they are junior to a first mtg, but superior to a second mtg.  If the hoa names the second mtg as a defendant, their mtg would be wiped out and they’d get any surplus.  But, hoa’s Never name a second mtg as a defendant, their mtg stays intact and the Owner gets any surplus.  I think perhaps the hoa’s never name the junior mtg so maybe the owner doesn’t fight them so hard, since they will get any surplus.  I’ve seen owner’s get surpluses from hoa foreclosures from $20-$70k.

See this reply in the discussion

35 Replies

Jump to latestLatest
  • Investor · Boca Raton, FL · Member since 2012 · 1k+ posts · 1k+ votes
    7y

    Judging by the looks of that subordination agreement, it was definitely a second mortgage foreclosure. Technically you are now the new title holder and subject to the First Mortgage. I would go into the county dockets to see if and when the borrower was served. You may want to get an attorney to do this for you to ensure the Foreclosure was carried out properly. If indeed it was done properly then you will need to either get a writ of possession and evict the borrower, or strike up a cash for keys agreement as you mentioned. You will then need to most likely pay off the First Mortgage.  That $30,000 Surplus will most likely go to the borrower minus any court or Sheriff sale fees.

  • Real Estate Professional · West Palm Beach, FL · Member since 2012 · 23k+ posts · 13k+ votes
    7y

    Yep, you bought at a second mtg foreclosure.  Assuming the sale IS proper, yes you own the property subject to the first mtg and are allowed to pay it off....they must give you a pay off amount and accept it.

    Your situation is somewhat rare, I’ve seen it twice, but Alabama when the “second mtg” was larger than the “first”.....so in those cases I always read the actual documents looking for a subordination clause.

  • Member since 2019 · 10 posts · 2 votes
    7y

    Question:

    Since I will have the deed from the 2nd mrg, in Illinois, cook county, am I able to pay off the 1st mrg no matter what, even if the owner is making monthly payments on the 1st mrg?

    Or do I have to evict him first so that he stops paying the 1st mrg and then once this happens the 1st mrg will be forced to go into foreclosure and I will have a chance to buy it?

  • Tyler GibsonBusiness Member
    Real Estate Agent · Orlando, FL · Member since 2017 · 1k+ posts · 2k+ votes
    7y

    @Pete Sloa assuming the courts side with you and state that the previous owner was properly notified then you are now responsible for the 1st MTG. If they side with him then you may have more time in court on your hands to get your money back. 

  • Real Estate Professional · West Palm Beach, FL · Member since 2012 · 23k+ posts · 13k+ votes
    7y

    @Pete Sloa I’d it turns out the foreclose was proper, the owner will realize he lost the property and will stop making payments, but who cares if he does keep making payments.  You’ll want to pay off the first, Not let it go to auction since the bids will likely be more than the $200k pay off which means you’d have to either bid higher or lose your $140k.

    Note, the only reason the bidding stopped at $140k is because the other bidders noticed this mtg was a second mtg due to the subordination.  If it’s worth $400k as is, the bidding will certainly go above $200k. 

  • George SkidisPro Member
    Rental Property Investor · Belleville, IL · Member since 2017 · 875 posts · 529 votes
    7y

    The voice of experience is always sweet. The advice of an smart attorney can be priceless. Since you did not get legal advice before moving into this "Maybe" it is time to look for some. Don't have the right kind of attorney? PM me for some ideas.

  • Investor · Boca Raton, FL · Member since 2012 · 1k+ posts · 1k+ votes
    7y
    Originally posted by @Pete Sloa:

    Question:

    Since I will have the deed from the 2nd mrg, in Illinois, cook county, am I able to pay off the 1st mrg no matter what, even if the owner is making monthly payments on the 1st mrg?

    Or do I have to evict him first so that he stops paying the 1st mrg and then once this happens the 1st mrg will be forced to go into foreclosure and I will have a chance to buy it?

    Yes you can try and contact the first mortgage holder and inform them you now own the property, which would invoke the due on sale clause. As Wayne mentions you do not want this to go to foreclosure in the risk that it goes to a third-party

  • Member since 2019 · 10 posts · 2 votes
    7y

    Another question:

    The $30K surplus will that go to the 1st mrg or to the owner?

    Or could the 2nd mrg just keep the surplus to themselves?

  • Paradise, CA · Member since 2015 · 1k+ posts · 871 votes
    7y
    Originally posted by @Pete Sloa:

    Another question:

    The $30K surplus will that go to the 1st mrg or to the owner?

    Or could the 2nd mrg just keep the surplus to themselves?

    It should go to the first, which should reduce the amount required to be paid off.

  • Investor · Boca Raton, FL · Member since 2012 · 1k+ posts · 1k+ votes
    7y
    Originally posted by @Ron S.:
    Originally posted by @Pete Sloa:

    Another question:

    The $30K surplus will that go to the 1st mrg or to the owner?

    Or could the 2nd mrg just keep the surplus to themselves?

    It should go to the first, which should reduce the amount required to be paid off. 

     Nope it goes to the borrower.  Surpluses are paid to the next successor lien in line, not predecessors and any left over to the borrower. 

  • Paradise, CA · Member since 2015 · 1k+ posts · 871 votes
    7y
    Originally posted by @Chad U.:
    Originally posted by @Ron S.:
    Originally posted by @Pete Sloa:

    Another question:

    The $30K surplus will that go to the 1st mrg or to the owner?

    Or could the 2nd mrg just keep the surplus to themselves?

    It should go to the first, which should reduce the amount required to be paid off. 

     Nope it goes to the borrower.  Surpluses are paid to the next successor lien in line, not predecessors and any left over to the borrower. 

     Exactly...the next successor lien in line is the former first lien-holder (now subordinated second lien-holder), not the borrower. So if the second lien-holder forecloses, and it sells to a third party for more than total debt, surplus funds go to the next lien-holder "creditor". Only when all liens are satisfied will surplus funds (If any) go back to the borrower.

    The priority of distribution is first to the cost of the first foreclosure, then to the lien-holder, then to subordinate lien holders in their order of priority. Since the senior subordinated at the time of their deed of trust there should be no question that they are next in priority. The only issue would be if someone tried to claim they had a priority right over the banks. If there are competing claims the court can interplead the funds. 

  • Lender · Ladera Ranch, CA · Member since 2014 · 1k+ posts · 1k+ votes
    7y

    @Ron S. If I'm reading the above correctly, the subordinated loan was originally a 1st mortgage but became the 2nd mortgage. Since that's the one that foreclosed, how does the mortgage that benefited become a junior lienholder? It seems to me that the loan that benefited from the subordination stays in senior position. With this logic, the excess proceeds from the foreclosure auction for the subordinated loan should go to any junior loans or, if none, to the borrower.

    @Pete Sloa I think you're learning your lesson that you need to know these things before you bid.

    Now, though, you need to protect your investment and you really do need expert advice to guide you through the rest of the process. I can recommend two different local attorneys that we use for our foreclosures. PM me for their contact info.

    I suspect that the owner knows more than he's letting on. I suggest that you look up the court case yourself. The case number should be easy to find on the documents related to the foreclosure sale and you can look up the court docket online for Cook County. You'll be able to tell right away if the owner "just hired" an attorney or has been contesting it the whole way. Since there's equity, I bet that the owner is going to fight and that his attorney will do everything he can to stall the confirmation of sale.

    When the confirmation looks imminent, the borrower may file BK on you and drag it out even further. Be prepared for a longer timeline. If you have pressure on your money, you might consider dropping out of this if you can get your deposit back. 

  • Paradise, CA · Member since 2015 · 1k+ posts · 871 votes
    7y
    Originally posted by @Andy Mirza:

    @Ron S. If I'm reading the above correctly, the subordinated loan was originally a 1st mortgage but became the 2nd mortgage. Since that's the one that foreclosed, how does the mortgage that benefited become a junior lienholder? It seems to me that the loan that benefited from the subordination stays in senior position. With this logic, the excess proceeds from the foreclosure auction for the subordinated loan should go to any junior loans or, if none, to the borrower.

    @Pete Sloa I think you're learning your lesson that you need to know these things before you bid.

    Now, though, you need to protect your investment and you really do need expert advice to guide you through the rest of the process. I can recommend two different local attorneys that we use for our foreclosures. PM me for their contact info.

    I suspect that the owner knows more than he's letting on. I suggest that you look up the court case yourself. The case number should be easy to find on the documents related to the foreclosure sale and you can look up the court docket online for Cook County. You'll be able to tell right away if the owner "just hired" an attorney or has been contesting it the whole way. Since there's equity, I bet that the owner is going to fight and that his attorney will do everything he can to stall the confirmation of sale.

    When the confirmation looks imminent, the borrower may file BK on you and drag it out even further. Be prepared for a longer timeline. If you have pressure on your money, you might consider dropping out of this if you can get your deposit back. 

    Whoever foreclosed would get their full debt paid, and whoever was in second, by design, by subordination or by default, would stand to get excess proceeds before the borrower would. I was only trying to make the point that borrower isn't getting anything and that whatever proceeds there were in excess of total debt of the foreclosing entity would go to the next lien-holder in line.

  • Member since 2019 · 10 posts · 2 votes
    7y
    Originally posted by @Ron S.:
    Originally posted by @Andy Mirza:

    @Ron S. If I'm reading the above correctly, the subordinated loan was originally a 1st mortgage but became the 2nd mortgage. Since that's the one that foreclosed, how does the mortgage that benefited become a junior lienholder? It seems to me that the loan that benefited from the subordination stays in senior position. With this logic, the excess proceeds from the foreclosure auction for the subordinated loan should go to any junior loans or, if none, to the borrower.

    @Pete Sloa I think you're learning your lesson that you need to know these things before you bid.

    Now, though, you need to protect your investment and you really do need expert advice to guide you through the rest of the process. I can recommend two different local attorneys that we use for our foreclosures. PM me for their contact info.

    I suspect that the owner knows more than he's letting on. I suggest that you look up the court case yourself. The case number should be easy to find on the documents related to the foreclosure sale and you can look up the court docket online for Cook County. You'll be able to tell right away if the owner "just hired" an attorney or has been contesting it the whole way. Since there's equity, I bet that the owner is going to fight and that his attorney will do everything he can to stall the confirmation of sale.

    When the confirmation looks imminent, the borrower may file BK on you and drag it out even further. Be prepared for a longer timeline. If you have pressure on your money, you might consider dropping out of this if you can get your deposit back. 

    Whoever foreclosed would get their full debt paid, and whoever was in second, by design, by subordination or by default, would stand to get excess proceeds before the borrower would. I was only trying to make the point that borrower isn't getting anything and that whatever proceeds there were in excess of total debt of the foreclosing entity would go to the next lien-holder in line.

     So in my case, since I bought 2nd mrg. The proceeds would first would go to any junior liens that are under 2nd mrg and the leftovers to the borrower/owner and NOT the 1st mrg?

    Still confused, is there any way that the 1st mrg can get the 30K surplus from the 2nd mrg foreslosure?

    Please note, that there are no other mrgs, just 1st and 2nd.

  • Real Estate Professional · West Palm Beach, FL · Member since 2012 · 23k+ posts · 13k+ votes
    7y

    @Ron S. It Was the second mtg holder (former first mtg, but subordinated their mtg) that foreclosed.  Since the remaining mtg is Superior to the foreclosing mtg holder, I don’t see them getting any surplus....they wouldn’t in FL, since their mtg stays intact.

    An interesting quirk in our foreclosure laws here....when an hoa forecloses, they are junior to a first mtg, but superior to a second mtg.  If the hoa names the second mtg as a defendant, their mtg would be wiped out and they’d get any surplus.  But, hoa’s Never name a second mtg as a defendant, their mtg stays intact and the Owner gets any surplus.  I think perhaps the hoa’s never name the junior mtg so maybe the owner doesn’t fight them so hard, since they will get any surplus.  I’ve seen owner’s get surpluses from hoa foreclosures from $20-$70k.

  • Paradise, CA · Member since 2015 · 1k+ posts · 871 votes
    7y
    Originally posted by @Wayne Brooks:

    @Ron S. It Was the second mtg holder (former first mtg, but subordinated their mtg) that foreclosed.  Since the remaining mtg is Superior to the foreclosing mtg holder, I don’t see them getting any surplus....they wouldn’t in FL, since their mtg stays intact.

    An interesting quirk in our foreclosure laws here....when an hoa forecloses, they are junior to a first mtg, but superior to a second mtg.  If the hoa names the second mtg as a defendant, their mtg would be wiped out and they’d get any surplus.  But, hoa’s Never name a second mtg as a defendant, their mtg stays intact and the Owner gets any surplus.  I think perhaps the hoa’s never name the junior mtg so maybe the owner doesn’t fight them so hard, since they will get any surplus.  I’ve seen owner’s get surpluses from hoa foreclosures from $20-$70k.

     I get your point. It will be interesting to see how Illinois plays this out.

  • Lender · Ladera Ranch, CA · Member since 2014 · 1k+ posts · 1k+ votes
    7y

    @Pete Sloa I think that most of us here agree that the excess proceeds will go to the previous owner/borrower. However, you really need to consult with an attorney who can provide specialized advice to you. 

  • Real Estate Consultant · 33033 · Member since 2018 · 65 posts · 23 votes
    7y

    Ok, so there are some things everyone might be overlooking (or i might be missing something here)

    Notice how the the lender is the same Harris Bank....I would bet $1 that the reason for the subordination is because the 200k loan recorded in 2009 is either a refinance or some type of heloc. 

    Banks do this so the mortgage with the highest amount not only gets priority butt conserve "value" in case the loan is sold. Now, i will bet $2 more dollars that Harris bank covered their but with the surplus by filing a special consideration in receiving a portion of any proceedings from a foreclosure auction by the second.

    Now, there are some states where if the second mortgage forecloses the first will still be able to collect surplus depending on the time the lis pend was filed 

    Funny gray area i my self have used to claim surplus (and got it) , the second foreclosed, before my first , which put my mortgage in a bad position BUT I COLLECTED THROUGH THE JUDGMENT which came next in line!

    in this case FOR SURE do not let the first foreclose. I would get in contact with the first make sure you find the special consideration ( i can almost assure you they filed) and get a payoff. 

    Hope I'm not misunderstanding what i read and are not being a contrarian to what everyone's thoughts for this case are.

    Best of luck!

  • Real Estate Consultant · 33033 · Member since 2018 · 65 posts · 23 votes
    7y

    To add....a second position will only foreclose when the property has enough equity to cover both mortgages such as in this case, and again...SAME LENDER! 

    Check the court docket, usually a first position can stop a junior lien (or just paying it off) in this case having equity and being the same lender they will allow it to proceed but by not contesting the case but requesting the consideration for surplus.

    Most likely Surplus will go to the 1st position.

  • Member since 2019 · 10 posts · 2 votes
    7y
    Originally posted by @Walter Holmes:

    To add....a second position will only foreclose when the property has enough equity to cover both mortgages such as in this case, and again...SAME LENDER! 

    Check the court docket, usually a first position can stop a junior lien (or just paying it off) in this case having equity and being the same lender they will allow it to proceed but by not contesting the case but requesting the consideration for surplus.

    Most likely Surplus will go to the 1st position.

    Yes, this is the same lender on both 1st and 2nd mrg. Do you know what kind of documents or in which document it would mention the consideration for the surplus?

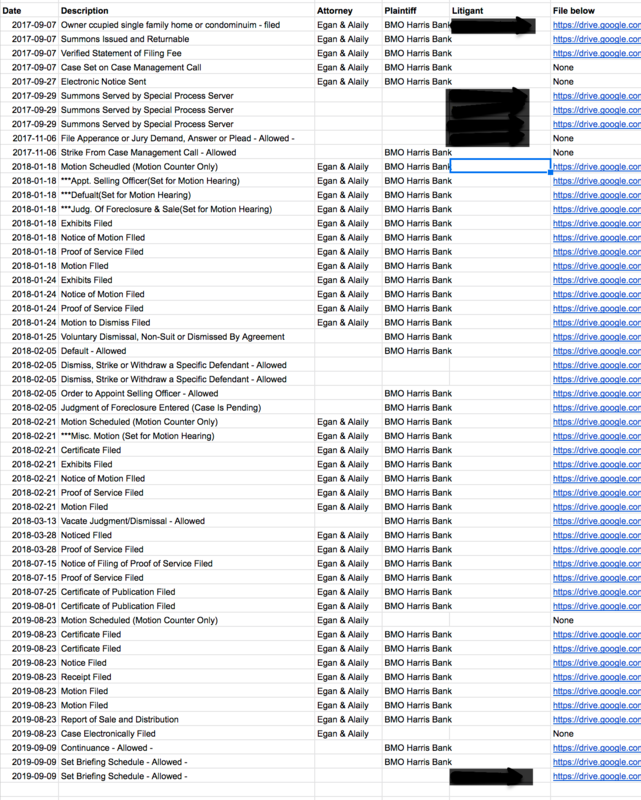
    I actually went to the court and took a pic of every single document and this is the order of the case:

  • Real Estate Consultant · 33033 · Member since 2018 · 65 posts · 23 votes
    7y

    Give me a sec, to go through the docket.

  • Lender · Ladera Ranch, CA · Member since 2014 · 1k+ posts · 1k+ votes
    7y

    @Walter Holmes This is good info to know. I've never had to deal with a subordinated loan before and, if I come across one, I'll know to look for the special clause on excess proceeds.

    @Pete Sloa Are you concerned about where the excess proceeds go because if it goes to the 1st, the amount owed to them decreases?

  • Member since 2019 · 10 posts · 2 votes
    7y
    Originally posted by @Andy Mirza:

    @Walter Holmes This is good info to know. I've never had to deal with a subordinated loan before and, if I come across one, I'll know to look for the special clause on excess proceeds.

    @Pete Sloa Are you concerned about where the excess proceeds go because if it goes to the 1st, the amount owed to them decreases?

    Yes, I would rather have it go to the 1st then to the owner. I still have to pay off the 1st but 30K less would be great.

  • Real Estate Professional · West Palm Beach, FL · Member since 2012 · 23k+ posts · 13k+ votes
    7y

    @Walter Holmes @Andy Mirza On this overage issue, being influenced by some mtg clause must be state specific.  Here, it wouldn’t matter what language you’d put in a mtg....surplus is awarded purely by state statutes, and no language in the mtg would affect this.

  • Lender · Ladera Ranch, CA · Member since 2014 · 1k+ posts · 1k+ votes
    7y

    @Bob Floss II Are you aware of any IL statutes that allow special clauses in mortgages to direct excess proceeds in a foreclosure sale backwards to a senior lien? In the case of this thread, one view here is that when a lender holds two mortgages against a property and subordinates one to the other, excess sales proceeds in a foreclosure sale can be directed back to the loan that's senior instead of going to junior lienholders. See prior posts for more detail.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.