Are you using projection models? (Here's why you should)

Are you using projection models? (Here's why you should)

Investor · Member since 2021 · 591 posts · 695 votes

Hey all,

Recently, I replied to a post asking folks whether they track their net worth. 

Personally, I do track my net worth. However, far more important to me are my financial projection models (which include projections about my net worth and many other variables over different time horizons). 

This got me wondering: how many BP folks are using projection models? If you're using projection models, what types of variables do you include? What types of time horizons do you cover? Why do you use projection models? What lessons have you learned from your projection models? How have projection models impacted your strategy?  Did you create your own projection models from the ground-up, or did you adapt someone else's existing models? Have your projections been accurate/inaccurate, and why?  ...if you're not using projection models, why not?

Here's a bit more info about my projection models, why they're so important, and why net worth (on its own) can be a completely misleading indicator of an investor's success:

Some of the main variables in my projection models include: expenses (broken down into various categories like personal expenses, capex, debt service, vacancy, etc.), income, cashflow, debt, DTI, equity, property appreciation, rent appreciation, mortgage paydown & amortization, rate of net worth growth, cost of living increases, hours worked per week, cash on hand, etc, etc.

I have short term (12-24 month), 5 year, 10 year, and 15 year projection models...sometimes I'll mess around with longer term (20+ years) projection models, but it's pretty difficult to project that far into the future, because there are so many unknown factors--so, the longer the projection model is, the less I tend to believe in its feasibility...

My projection models allow me to make more informed decisions about things like: whether to buy or sell a particular property, whether to refi a property, whether to rehab a property, whether to pursue or abandon a particular revenue stream, how to approach rent increases, how to manage risks, what debt to pay down first, whether a particular goal is worth the amount of hours I'll need to work to achieve the goal, what my goals should be, how to achieve various goals as efficiently as possible, etc., etc. 

In a nutshell, good projection models help you strategize. Sometimes the strategy the models reveal is to DO certain things (like rehab a property), but sometimes the strategy they reveal is to do nothing. Indeed, I recently ran some models that showed me that the best strategy for me, in certain areas of my portfolio, is to simply do nothing--don't make any big moves, just let things progress as they are...

A good projection model will show you not only how to reach various goals, but it also all sorts of potential roadblocks that could prevent you from reaching goals (as well as potential solutions to those problems). Projection models allow you to answer all sorts of "If I do X, what will happen in Y years?"-type questions.

I run projection models that include disaster scenarios (e.g.; a massive '08-style collapse in prices), as well as best-case dream scenarios...however, MOST of my projection models focus on fairly modest outcomes (such as 2-4% property appreciation, 2-4% rent growth, etc.). It's these more modest, relatively conservative models that are the "meat and potatoes" of my strategizing.

Although net worth is part of my models, and many investors love to brag on their net worths, net worth can be an incredibly misleading number. Consider two hypothetical investors:

Investor A tells you "my net worth is $10 mil". That may sound pretty good...until you discover that their net worth is decreasing at a rate of $2 million per year, and they've got $100 mil of adjustable rate debt on a portfolio of D class properties that forces them to work 80+ hours per week just to keep the whole thing afloat...

Investor B tells you "my net worth is $1 mil" --to many successful investors, that sounds like a relatively insignificant net worth...but, investor B owns a portfolio of A class properties with zero debt, professionally managed, their cashflow is $500k per year, their net worth is increasing at a rate of $1 mil per year, and they only have to work about 1-2 hours per week to keep their machine going.

Personally, I'd MUCH rather be investor B than investor A (even though investor A's net worth is 10x of investor B's).

So yeah, tracking net worth is advisable, but it's only a small part of what an investor should be tracking and modeling, and net worth alone might not be very indicative of an investor's success...

An effective investor creates models to help them strategize, and those models inevitably include net worth, but they include a LOT more than just net worth (and as a result, they can be quite time-intensive to create)...but, the things that are most worth doing usually ain't easy...

4Reply
73 views

Most Popular Reply

Byron VallesPro Member
MSFP, CFP, Financial Advisor · San Francisco Bay Area · Member since 2020 · 66 posts · 53 votes
2y
Quote from @Leo R.:

Hey all,

Recently, I replied to a post asking folks whether they track their net worth. 

Personally, I do track my net worth. However, far more important to me are my financial projection models (which include projections about my net worth and many other variables over different time horizons). 

This got me wondering: how many BP folks are using projection models? If you're using projection models, what types of variables do you include? What types of time horizons do you cover? Why do you use projection models? What lessons have you learned from your projection models? How have projection models impacted your strategy?  Did you create your own projection models from the ground-up, or did you adapt someone else's existing models? Have your projections been accurate/inaccurate, and why?  ...if you're not using projection models, why not?

Here's a bit more info about my projection models, why they're so important, and why net worth (on its own) can be a completely misleading indicator of an investor's success:

Some of the main variables in my projection models include: expenses (broken down into various categories like personal expenses, capex, debt service, vacancy, etc.), income, cashflow, debt, DTI, equity, property appreciation, rent appreciation, mortgage paydown & amortization, rate of net worth growth, cost of living increases, hours worked per week, cash on hand, etc, etc.

I have short term (12-24 month), 5 year, 10 year, and 15 year projection models...sometimes I'll mess around with longer term (20+ years) projection models, but it's pretty difficult to project that far into the future, because there are so many unknown factors--so, the longer the projection model is, the less I tend to believe in its feasibility...

My projection models allow me to make more informed decisions about things like: whether to buy or sell a particular property, whether to refi a property, whether to rehab a property, whether to pursue or abandon a particular revenue stream, how to approach rent increases, how to manage risks, what debt to pay down first, whether a particular goal is worth the amount of hours I'll need to work to achieve the goal, what my goals should be, how to achieve various goals as efficiently as possible, etc., etc. 

In a nutshell, good projection models help you strategize. Sometimes the strategy the models reveal is to DO certain things (like rehab a property), but sometimes the strategy they reveal is to do nothing. Indeed, I recently ran some models that showed me that the best strategy for me, in certain areas of my portfolio, is to simply do nothing--don't make any big moves, just let things progress as they are...

A good projection model will show you not only how to reach various goals, but it also all sorts of potential roadblocks that could prevent you from reaching goals (as well as potential solutions to those problems). Projection models allow you to answer all sorts of "If I do X, what will happen in Y years?"-type questions.

I run projection models that include disaster scenarios (e.g.; a massive '08-style collapse in prices), as well as best-case dream scenarios...however, MOST of my projection models focus on fairly modest outcomes (such as 2-4% property appreciation, 2-4% rent growth, etc.). It's these more modest, relatively conservative models that are the "meat and potatoes" of my strategizing.

Although net worth is part of my models, and many investors love to brag on their net worths, net worth can be an incredibly misleading number. Consider two hypothetical investors:

Investor A tells you "my net worth is $10 mil". That may sound pretty good...until you discover that their net worth is decreasing at a rate of $2 million per year, and they've got $100 mil of adjustable rate debt on a portfolio of D class properties that forces them to work 80+ hours per week just to keep the whole thing afloat...

Investor B tells you "my net worth is $1 mil" --to many successful investors, that sounds like a relatively insignificant net worth...but, investor B owns a portfolio of A class properties with zero debt, professionally managed, their cashflow is $500k per year, their net worth is increasing at a rate of $1 mil per year, and they only have to work about 1-2 hours per week to keep their machine going.

Personally, I'd MUCH rather be investor B than investor A (even though investor A's net worth is 10x of investor B's).

So yeah, tracking net worth is advisable, but it's only a small part of what an investor should be tracking and modeling, and net worth alone might not be very indicative of an investor's success...

An effective investor creates models to help them strategize, and those models inevitably include net worth, but they include a LOT more than just net worth (and as a result, they can be quite time-intensive to create)...but, the things that are most worth doing usually ain't easy...


 Great post, Leo. I run financial projections for the families I serve using a planning software called eMoney. Some of the variables that go into the software include expenses broken down to as many details as they prefer, different types of income, assets, liabilities, different growth rates, etc. The software can produce many detailed reports but the ones I include for most families are cash flow, net worth, estate calculations, tax reports, etc. What I've found is that while the reports produced by the modeling software are helpful, they are not without limitations. 

As you mentioned, I've found that modeling projections for more than 15 years into the future is not as helpful. Especially for young folks. For those people, I've found that using software and presenting all kinds of different reports is overkill, it can frankly become confusing and overwhelming (imagine having a conversation with a 30-year-old about their estate calculation 40+ years into the future). Instead, I built a simpler Excel model with variables like their asset balances, any contributions/debt paydown, growth rates, and future value calculations for different time frames not exceeding 15 years. I use this simpler model to supplement the educational conversations we have about good financial habits. 

The other limitation I've found with eMoney (and many other professional software) is that they do handle basic real estate projections like depreciation, amortization schedules, income/expenses, net equity, etc. However, the software is designed to produce reports and projections from property already owned. In other words, you can't use it to analyze potential deals. So I build an Excel model for that. 

Lastly, I couldn't agree more with you regarding some of the drawbacks of models. They take a long time to build and refine if built by hand and you have to understand the calculations and assumptions behind them. 

See this reply in the discussion

16 Replies

Jump to latestLatest
  • Wholesaler · Natchitoches-71457, LA · Member since 2023 · 7 posts · 0 votes
    2y

    How do you create a projection model or where do you get one from?

  • Investor · Member since 2021 · 591 posts · 695 votes
    2y

    @Riko Roberson I built mine from the ground up in Excel. One advantage of building it from the ground up is that I thoroughly understand the model, its calculations, its limitations/blind spots, its usage, etc. (because I built it).

    On the downside, I'm not an Excel expert, so I'm sure a serious Excel pro could create a model that's much better-designed than mine...and there are also probably programs that would be better-suited to the task than Excel (I just used Excel because I have some understanding of it, but I had no understanding of the other software options). 

    The first models I made weren't very good (they had a lot of blind spots, weird quirks, inefficient ways of calculating things, etc.), but I improved them over the years, and now they're a lot better (though still far from perfect).

    Although my models aren't perfect, they've still been incredibly useful--they've allowed me to capitalize on some significant opportunities, and also avoid a few serious mistakes. They also give me a sense of direction--I don't get lost in analysis paralysis, because the models basically give me a step-by-step roadmap of what to do..."If I do X, then in Y years, Z will occur, and we're 85% sure of that outcome, based on the model"

    There are definitely times a model has been incorrect (it predicted something, but the real outcome was different)...but, even when a model is wrong, it teaches you something--and with that info, you can make even better models.

    Another drawback of building the models myself is that it took a lot of time--I probably could have saved time by adapting an existing model...I initially tried to adapt some existing models I found online, but they weren't easily adaptable to my specific circumstances/variables/goals/usage--which is why I ended up building my own models...

  • Chris SeveneyBusiness Member
    Moderator
    Investor · VA · Member since 2015 · 21k+ posts · 19k+ votes
    2y

    @Riko Roberson

    Getrefm.com is great place to learn how to model in excel

    7e investments53 Reviews
  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    2y

    depends on age I guess.. I am too old to be thinking about decades in the future :)

  • Investor · Member since 2021 · 591 posts · 695 votes
    2y

    @Jay Hinrichs do you run any near-term models? ...stuff that's 6-24 months?

  • Jay HinrichsBusiness Member
    Real Estate Consultant · Summerlin, NV · Member since 2014 · 45k+ posts · 66k+ votes
    2y
    Quote from @Leo R.:

    @Jay Hinrichs do you run any near-term models? ...stuff that's 6-24 months?


    NO.   I run them daily in my head.. Keep in mind we are not landlords per se and the rentals we have are paid for A class.. so much to those.. our main income is providing BRRR financing to flippers and we have a project in Oregon www.Ivyridgeestatescanby.com  90 new homes although we are 60% or so through it.. In this market its hard to model out sales.. but when I went into it I did model it at 2 sales a month and we have done justs about that our starting prices were 550 to 650 3 years ago.. today we are 650 to 950k same models.. so end profit far exceeds original proforma's that we did for our banks.
  • Byron VallesPro Member
    MSFP, CFP, Financial Advisor · San Francisco Bay Area · Member since 2020 · 66 posts · 53 votes
    2y
    Quote from @Leo R.:

    Hey all,

    Recently, I replied to a post asking folks whether they track their net worth. 

    Personally, I do track my net worth. However, far more important to me are my financial projection models (which include projections about my net worth and many other variables over different time horizons). 

    This got me wondering: how many BP folks are using projection models? If you're using projection models, what types of variables do you include? What types of time horizons do you cover? Why do you use projection models? What lessons have you learned from your projection models? How have projection models impacted your strategy?  Did you create your own projection models from the ground-up, or did you adapt someone else's existing models? Have your projections been accurate/inaccurate, and why?  ...if you're not using projection models, why not?

    Here's a bit more info about my projection models, why they're so important, and why net worth (on its own) can be a completely misleading indicator of an investor's success:

    Some of the main variables in my projection models include: expenses (broken down into various categories like personal expenses, capex, debt service, vacancy, etc.), income, cashflow, debt, DTI, equity, property appreciation, rent appreciation, mortgage paydown & amortization, rate of net worth growth, cost of living increases, hours worked per week, cash on hand, etc, etc.

    I have short term (12-24 month), 5 year, 10 year, and 15 year projection models...sometimes I'll mess around with longer term (20+ years) projection models, but it's pretty difficult to project that far into the future, because there are so many unknown factors--so, the longer the projection model is, the less I tend to believe in its feasibility...

    My projection models allow me to make more informed decisions about things like: whether to buy or sell a particular property, whether to refi a property, whether to rehab a property, whether to pursue or abandon a particular revenue stream, how to approach rent increases, how to manage risks, what debt to pay down first, whether a particular goal is worth the amount of hours I'll need to work to achieve the goal, what my goals should be, how to achieve various goals as efficiently as possible, etc., etc. 

    In a nutshell, good projection models help you strategize. Sometimes the strategy the models reveal is to DO certain things (like rehab a property), but sometimes the strategy they reveal is to do nothing. Indeed, I recently ran some models that showed me that the best strategy for me, in certain areas of my portfolio, is to simply do nothing--don't make any big moves, just let things progress as they are...

    A good projection model will show you not only how to reach various goals, but it also all sorts of potential roadblocks that could prevent you from reaching goals (as well as potential solutions to those problems). Projection models allow you to answer all sorts of "If I do X, what will happen in Y years?"-type questions.

    I run projection models that include disaster scenarios (e.g.; a massive '08-style collapse in prices), as well as best-case dream scenarios...however, MOST of my projection models focus on fairly modest outcomes (such as 2-4% property appreciation, 2-4% rent growth, etc.). It's these more modest, relatively conservative models that are the "meat and potatoes" of my strategizing.

    Although net worth is part of my models, and many investors love to brag on their net worths, net worth can be an incredibly misleading number. Consider two hypothetical investors:

    Investor A tells you "my net worth is $10 mil". That may sound pretty good...until you discover that their net worth is decreasing at a rate of $2 million per year, and they've got $100 mil of adjustable rate debt on a portfolio of D class properties that forces them to work 80+ hours per week just to keep the whole thing afloat...

    Investor B tells you "my net worth is $1 mil" --to many successful investors, that sounds like a relatively insignificant net worth...but, investor B owns a portfolio of A class properties with zero debt, professionally managed, their cashflow is $500k per year, their net worth is increasing at a rate of $1 mil per year, and they only have to work about 1-2 hours per week to keep their machine going.

    Personally, I'd MUCH rather be investor B than investor A (even though investor A's net worth is 10x of investor B's).

    So yeah, tracking net worth is advisable, but it's only a small part of what an investor should be tracking and modeling, and net worth alone might not be very indicative of an investor's success...

    An effective investor creates models to help them strategize, and those models inevitably include net worth, but they include a LOT more than just net worth (and as a result, they can be quite time-intensive to create)...but, the things that are most worth doing usually ain't easy...


     Great post, Leo. I run financial projections for the families I serve using a planning software called eMoney. Some of the variables that go into the software include expenses broken down to as many details as they prefer, different types of income, assets, liabilities, different growth rates, etc. The software can produce many detailed reports but the ones I include for most families are cash flow, net worth, estate calculations, tax reports, etc. What I've found is that while the reports produced by the modeling software are helpful, they are not without limitations. 

    As you mentioned, I've found that modeling projections for more than 15 years into the future is not as helpful. Especially for young folks. For those people, I've found that using software and presenting all kinds of different reports is overkill, it can frankly become confusing and overwhelming (imagine having a conversation with a 30-year-old about their estate calculation 40+ years into the future). Instead, I built a simpler Excel model with variables like their asset balances, any contributions/debt paydown, growth rates, and future value calculations for different time frames not exceeding 15 years. I use this simpler model to supplement the educational conversations we have about good financial habits. 

    The other limitation I've found with eMoney (and many other professional software) is that they do handle basic real estate projections like depreciation, amortization schedules, income/expenses, net equity, etc. However, the software is designed to produce reports and projections from property already owned. In other words, you can't use it to analyze potential deals. So I build an Excel model for that. 

    Lastly, I couldn't agree more with you regarding some of the drawbacks of models. They take a long time to build and refine if built by hand and you have to understand the calculations and assumptions behind them. 

  • Investor · Member since 2021 · 591 posts · 695 votes
    2y
    Quote from @Byron Valles:
    Quote from @Leo R.:

    Hey all,

    Recently, I replied to a post asking folks whether they track their net worth. 

    Personally, I do track my net worth. However, far more important to me are my financial projection models (which include projections about my net worth and many other variables over different time horizons). 

    This got me wondering: how many BP folks are using projection models? If you're using projection models, what types of variables do you include? What types of time horizons do you cover? Why do you use projection models? What lessons have you learned from your projection models? How have projection models impacted your strategy?  Did you create your own projection models from the ground-up, or did you adapt someone else's existing models? Have your projections been accurate/inaccurate, and why?  ...if you're not using projection models, why not?

    Here's a bit more info about my projection models, why they're so important, and why net worth (on its own) can be a completely misleading indicator of an investor's success:

    Some of the main variables in my projection models include: expenses (broken down into various categories like personal expenses, capex, debt service, vacancy, etc.), income, cashflow, debt, DTI, equity, property appreciation, rent appreciation, mortgage paydown & amortization, rate of net worth growth, cost of living increases, hours worked per week, cash on hand, etc, etc.

    I have short term (12-24 month), 5 year, 10 year, and 15 year projection models...sometimes I'll mess around with longer term (20+ years) projection models, but it's pretty difficult to project that far into the future, because there are so many unknown factors--so, the longer the projection model is, the less I tend to believe in its feasibility...

    My projection models allow me to make more informed decisions about things like: whether to buy or sell a particular property, whether to refi a property, whether to rehab a property, whether to pursue or abandon a particular revenue stream, how to approach rent increases, how to manage risks, what debt to pay down first, whether a particular goal is worth the amount of hours I'll need to work to achieve the goal, what my goals should be, how to achieve various goals as efficiently as possible, etc., etc. 

    In a nutshell, good projection models help you strategize. Sometimes the strategy the models reveal is to DO certain things (like rehab a property), but sometimes the strategy they reveal is to do nothing. Indeed, I recently ran some models that showed me that the best strategy for me, in certain areas of my portfolio, is to simply do nothing--don't make any big moves, just let things progress as they are...

    A good projection model will show you not only how to reach various goals, but it also all sorts of potential roadblocks that could prevent you from reaching goals (as well as potential solutions to those problems). Projection models allow you to answer all sorts of "If I do X, what will happen in Y years?"-type questions.

    I run projection models that include disaster scenarios (e.g.; a massive '08-style collapse in prices), as well as best-case dream scenarios...however, MOST of my projection models focus on fairly modest outcomes (such as 2-4% property appreciation, 2-4% rent growth, etc.). It's these more modest, relatively conservative models that are the "meat and potatoes" of my strategizing.

    Although net worth is part of my models, and many investors love to brag on their net worths, net worth can be an incredibly misleading number. Consider two hypothetical investors:

    Investor A tells you "my net worth is $10 mil". That may sound pretty good...until you discover that their net worth is decreasing at a rate of $2 million per year, and they've got $100 mil of adjustable rate debt on a portfolio of D class properties that forces them to work 80+ hours per week just to keep the whole thing afloat...

    Investor B tells you "my net worth is $1 mil" --to many successful investors, that sounds like a relatively insignificant net worth...but, investor B owns a portfolio of A class properties with zero debt, professionally managed, their cashflow is $500k per year, their net worth is increasing at a rate of $1 mil per year, and they only have to work about 1-2 hours per week to keep their machine going.

    Personally, I'd MUCH rather be investor B than investor A (even though investor A's net worth is 10x of investor B's).

    So yeah, tracking net worth is advisable, but it's only a small part of what an investor should be tracking and modeling, and net worth alone might not be very indicative of an investor's success...

    An effective investor creates models to help them strategize, and those models inevitably include net worth, but they include a LOT more than just net worth (and as a result, they can be quite time-intensive to create)...but, the things that are most worth doing usually ain't easy...


     Great post, Leo. I run financial projections for the families I serve using a planning software called eMoney. Some of the variables that go into the software include expenses broken down to as many details as they prefer, different types of income, assets, liabilities, different growth rates, etc. The software can produce many detailed reports but the ones I include for most families are cash flow, net worth, estate calculations, tax reports, etc. What I've found is that while the reports produced by the modeling software are helpful, they are not without limitations. 

    As you mentioned, I've found that modeling projections for more than 15 years into the future is not as helpful. Especially for young folks. For those people, I've found that using software and presenting all kinds of different reports is overkill, it can frankly become confusing and overwhelming (imagine having a conversation with a 30-year-old about their estate calculation 40+ years into the future). Instead, I built a simpler Excel model with variables like their asset balances, any contributions/debt paydown, growth rates, and future value calculations for different time frames not exceeding 15 years. I use this simpler model to supplement the educational conversations we have about good financial habits. 

    The other limitation I've found with eMoney (and many other professional software) is that they do handle basic real estate projections like depreciation, amortization schedules, income/expenses, net equity, etc. However, the software is designed to produce reports and projections from property already owned. In other words, you can't use it to analyze potential deals. So I build an Excel model for that. 

    Lastly, I couldn't agree more with you regarding some of the drawbacks of models. They take a long time to build and refine if built by hand and you have to understand the calculations and assumptions behind them. 


    Yeah, an important thing to point out for the folks who haven't yet done any projection models is that an investor doesn't have just ONE projection model...I have MANY projection models, with different scenarios plugged in, and I'm constantly editing and improving my primary models...  My primary models have evolved over years of countless edits, re-assessments, new info, etc.

  • Member since 2023 · 1 post · 1 vote
    2y

    Could you provide a screenshot of your spreadsheet with dummy data.

  • Wholesaler · Natchitoches-71457, LA · Member since 2023 · 7 posts · 0 votes
    2y
    Quote from @Leo R.:

    @Riko Roberson I built mine from the ground up in Excel. One advantage of building it from the ground up is that I thoroughly understand the model, its calculations, its limitations/blind spots, its usage, etc. (because I built it).

    On the downside, I'm not an Excel expert, so I'm sure a serious Excel pro could create a model that's much better-designed than mine...and there are also probably programs that would be better-suited to the task than Excel (I just used Excel because I have some understanding of it, but I had no understanding of the other software options). 

    The first models I made weren't very good (they had a lot of blind spots, weird quirks, inefficient ways of calculating things, etc.), but I improved them over the years, and now they're a lot better (though still far from perfect).

    Although my models aren't perfect, they've still been incredibly useful--they've allowed me to capitalize on some significant opportunities, and also avoid a few serious mistakes. They also give me a sense of direction--I don't get lost in analysis paralysis, because the models basically give me a step-by-step roadmap of what to do..."If I do X, then in Y years, Z will occur, and we're 85% sure of that outcome, based on the model"

    There are definitely times a model has been incorrect (it predicted something, but the real outcome was different)...but, even when a model is wrong, it teaches you something--and with that info, you can make even better models.

    Another drawback of building the models myself is that it took a lot of time--I probably could have saved time by adapting an existing model...I initially tried to adapt some existing models I found online, but they weren't easily adaptable to my specific circumstances/variables/goals/usage--which is why I ended up building my own models...


     Thank you, that was very informative.  I'm getting more into it and I find it very interesting as well.  

  • Wholesaler · Natchitoches-71457, LA · Member since 2023 · 7 posts · 0 votes
    2y
    Quote from @Chris Seveney:

    @Riko Roberson

    Getrefm.com is great place to learn how to model in excel

    thank you, very much


  • Specialist · LA & Ventura · Member since 2023 · 119 posts · 60 votes
    2y

    @Leo R. Your post title got me excited, but after reading through it, seems lacking. I mean where is your model so we can get an idea of what you're referring to?

    Projection models? Do you mean what rent prices or $/sf will be in 1-2 years, for your specific property/properties? Seems like a fools errand, just underwrite it at current-values, if it pencils for you (either in flip profit or CF return by holding) buy it, and build/improve it. If you hit your numbers, you should sell (unless it meets/exceeds your CF return thresholds), capture that value, & move on to the next. If you don't hit your numbers (construction took too long, was more than expected, no offers coming in, etc) then you have to stick to the rental CF and wait for appreciation (in either rents or $/sf) to get you out of the deal profitably.

    Bottom line is your model is only as good as what you put in it, and you can only be 100% certain about Today's values/rents/rates/etc. If it doesn't make sense with that, you are entering the realm of wishful thinking.

    I do value-add development, mostly fix & flips, some new builds, and hold 3-4 unit rentals we built from a 1-unit SFR via ADUs.

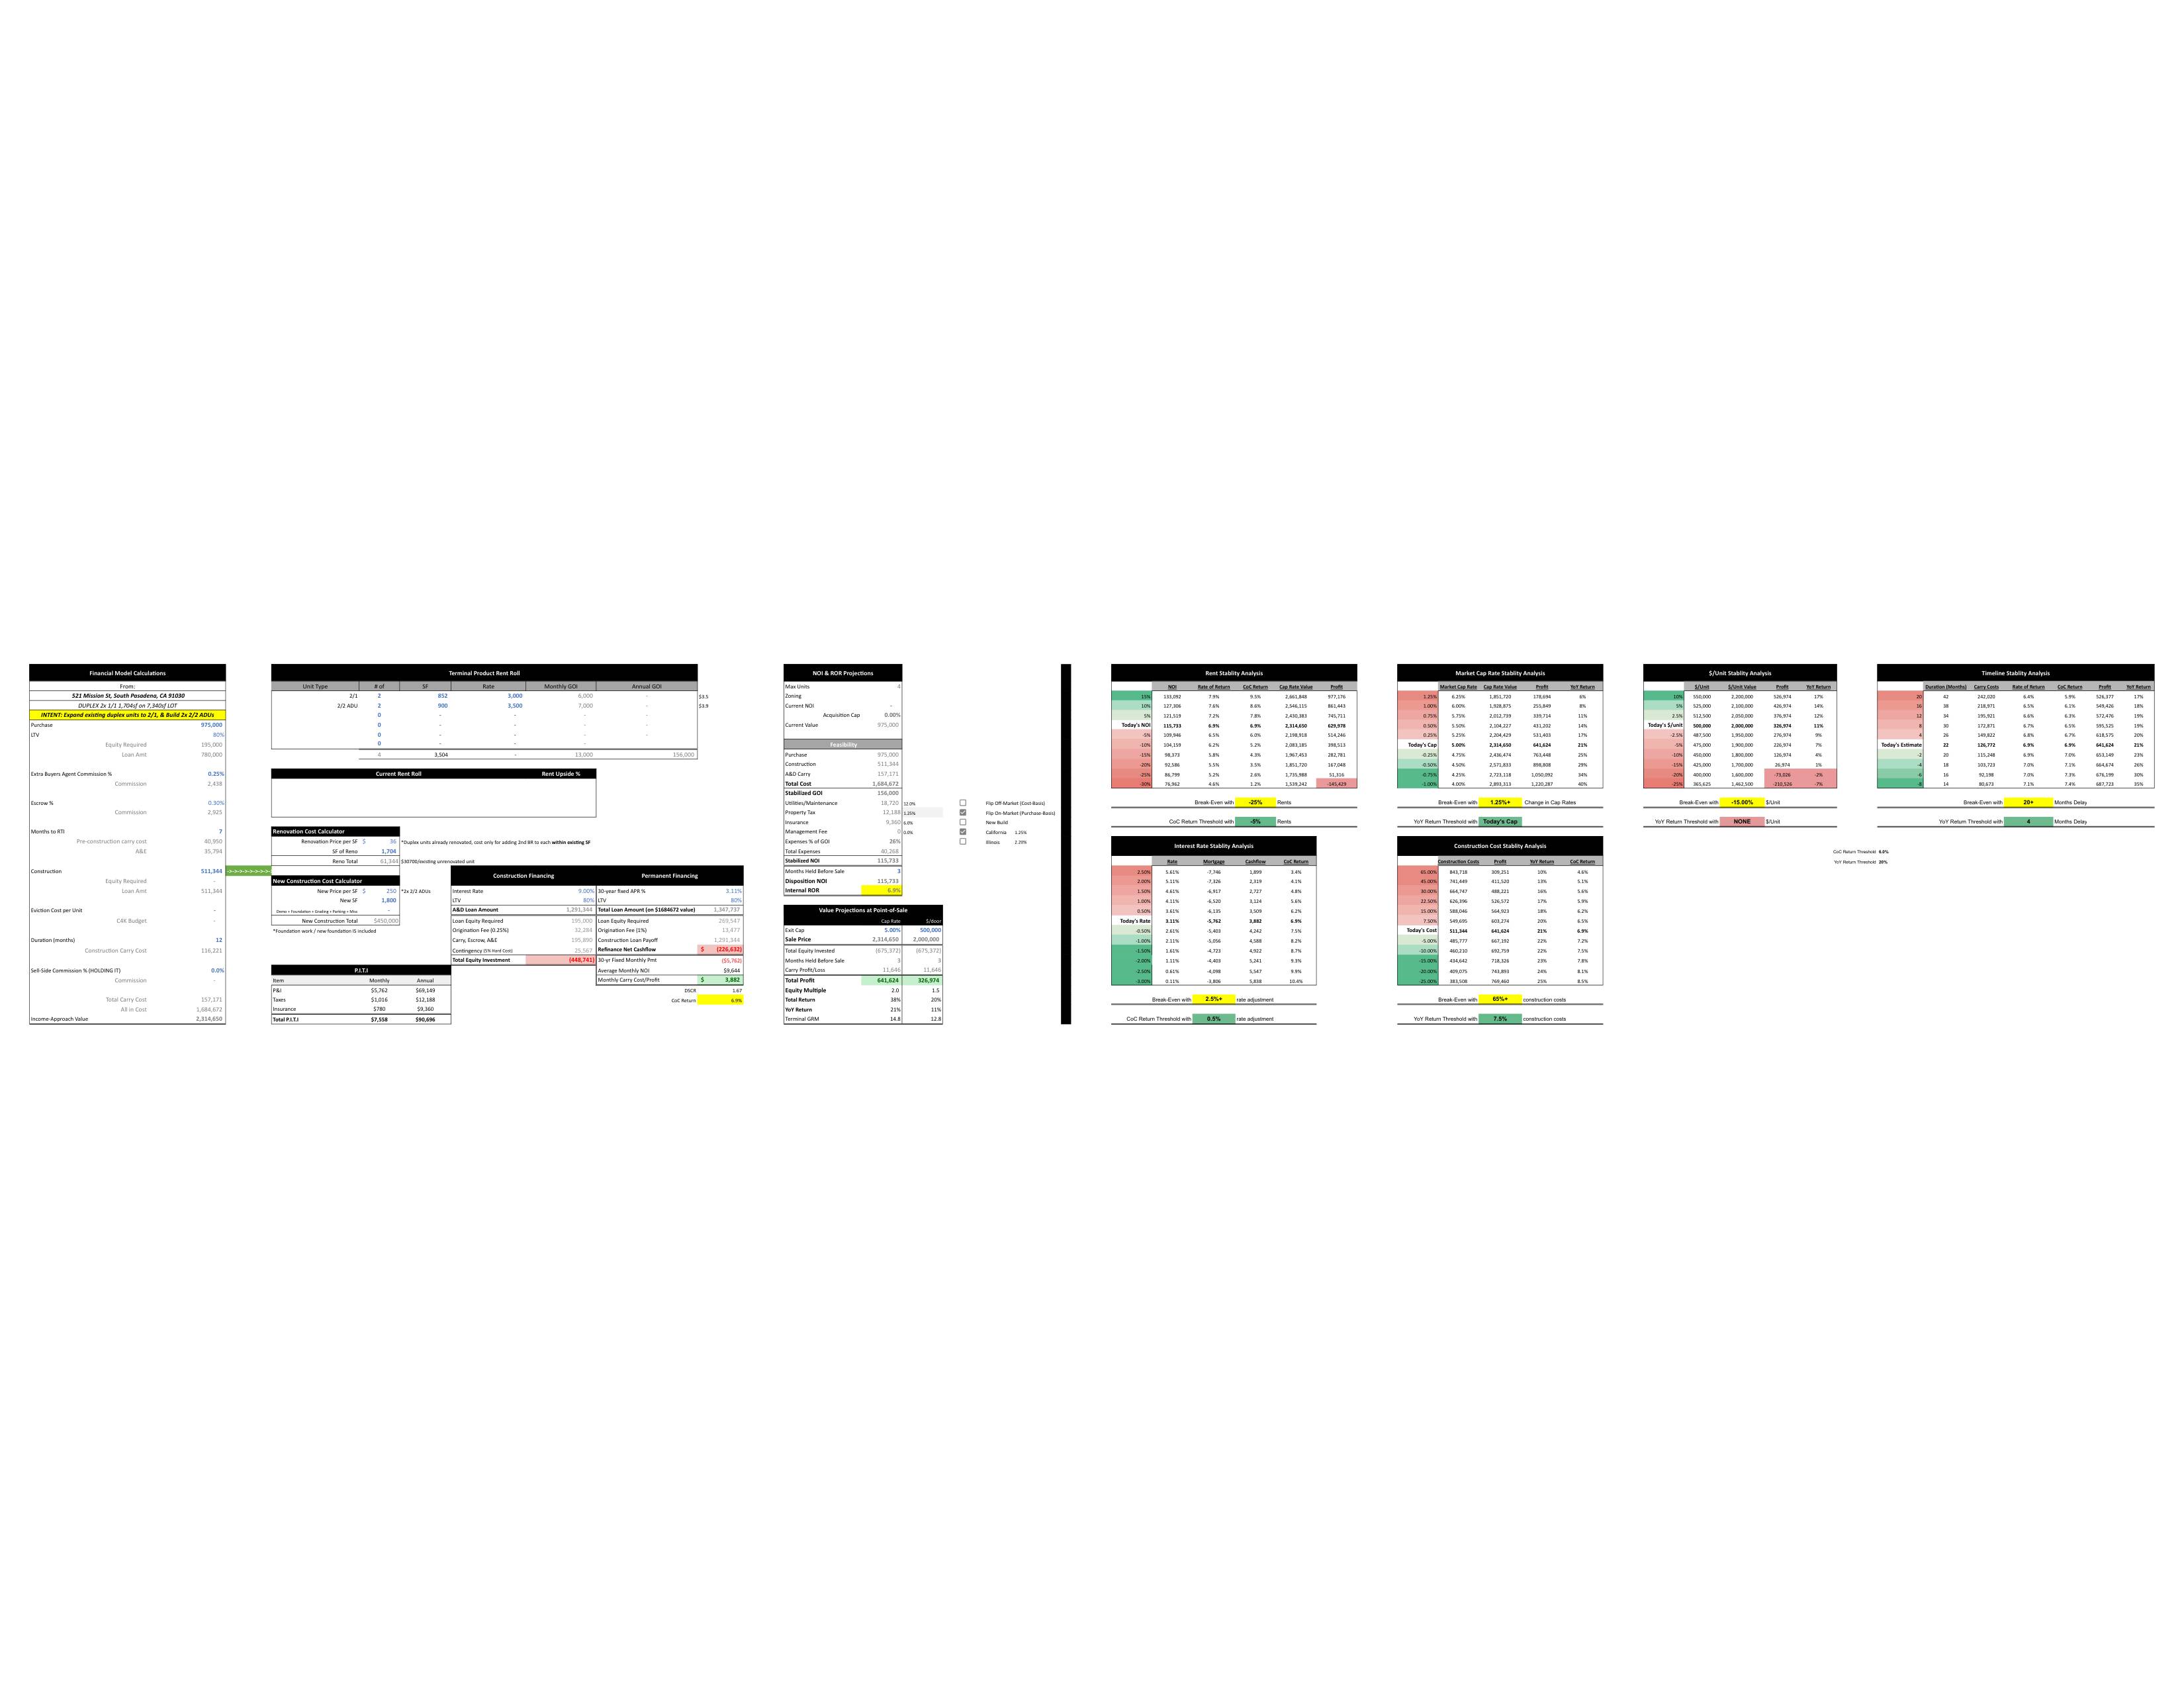
    Here's my fix and flip model (which 'Projects' my return should the terminal-value change upon delivering the product to market, allowing me to better visualize the risk of the deal):


    And here's my MF hold/flip model (just shows me the key-metrics at today's values so I can ensure I'm offering at a price which suits our desired return thresholds upon sale or hold):

    In my MF model, there is a 'Months held before Sale' that will increase the NOI by 3% every 12 months, but that is the only 'Projection' in this model, and I practically never use it:

    For projecting if a market (and respective deal) is good, I have to look at market-analysis data metrics (absorption, $/sf, rents, etc, all over time, so you can see if something is peaking or undervalued). Typically absorption is tied to $/sf, longer DOM is indicative of the market slowing down, etc. No excel model will show you this stuff, you have to get it elsewhere, so I am curious what you are 'Projecting' off of, and what usefulness you yield from these 'Projections'. In my mind, you should run all possible development schemes/projections up-front, before the purchase, and embark on the most profitable one from the start.

  • Investor · Member since 2021 · 591 posts · 695 votes
    2y

    @Steven S. my models project things like rent growth, property appreciation, net worth, etc.--see my original post for more details on the types of variables my models include.

    ...but, the type of models that work for me probably won't work for other investors, because everyone has different circumstances, goals, portfolios, variables of interest, risk exposures, etc., etc. (which, again, is why I ended up creating my own models from the ground up instead of trying to adapt someone else's model to fit my needs).

    As I mentioned, I have "meat and potatoes" models that are pretty in-line with reasonable expectations (like 2% appreciation), but I also have more extreme "disaster" and "dream scenario" models. I obviously place much less weight on the extreme models (i.e., I don't make any life plans expecting repeated 15% YOY rent growth or anything like that), but it is still useful to run the extreme models to get a sense of what could happen in various disasters or big market upswings...sometimes an extreme model (like a disaster model) might show you that things wouldn't be as bad as you thought during a big crash (and now you can sleep easier)...or, it might show you that things would be much worse than you thought--in which case, the model at least provides a better understanding of how to prepare for the worst.

    For me, the models are less about making a perfect prediction of what will happen in the future (often not possible), and more about gaining a deeper understanding of my portfolio's current position, and the range of possible outcomes that could occur for my portfolio over various time frames, given different variables (like rehabs, rent changes, refis, sales, acquisitions, etc.). In other words, it's more about improving my understanding of what COULD happen, not necessarily what WILL happen. 

    It also helps me understand how to optimize my portfolio, how to capitalize on opportunities, and how to avoid mistakes. For example, I've run models that showed me that a particular rehab wasn't going to produce the type of return I originally thought, and that I'd be better off dropping that capital on a different property in the portfolio...  I've run models to assess the outcomes of certain moves (like buying, selling, refi'ing, rehabbing), and sometimes those models have revealed that the best course of action was to do none of those moves, and instead simply sit still and relax...

    So again, for me, creating projection models is more about gaining a better understanding of where my portfolio sits, and the outcomes that could occur in the future--not necessarily about trying to make a perfect prediction of the future. Once I learn what possible outcomes could occur, I can create strategies to make the outcomes I want happen, and create strategies to avoid the outcomes I want to avoid. 

    My over-arching goal is a portfolio with zero debt, enough equity to cushion me from pretty much any financial setback, predictable and significant annual increases to net worth, enough cashflow to sustain a very, very comfortable lifestyle and meaningful philanthropic initiatives (without any obligation to work a W2 job or bring in any other income), and which doesn't require more than one or two hours per week for me to manage. So far, I'm on track to achieve that goal relatively soon, and the projection models have been key in helping me figure out how to achieve that goal as efficiently as possible...so yeah, I can't recommend projection models enough--particularly to investors who are just getting started. If nothing else, you'll learn by creating projection models--and that, in and of itself, is usually a worthwhile use of time.

  • Specialist · LA & Ventura · Member since 2023 · 119 posts · 60 votes
    2y
    Quote from @Leo R.:

    For example, I've run models that showed me that a particular rehab wasn't going to produce the type of return I originally thought, and that I'd be better off dropping that capital on a different property in the portfolio...

    My point was that you'd have to manually re-run your metrics (rent comps, sales values, refi rates, and rehab costs) on every property, every time you want to re-assess. For example, you'd have to see what the top-of-market rents are for your specific units/product, then update that in your model, add in the costs, and see if that increases your return metrics enough to be worthwhile. Then update the new sales comps, see what those are trading for on a $/sf, cap rate, and $/unit basis, and so on to make sure you are actually adding real value.

    Why not just assess at the time of purchase? Do you own that many properties that are not at top-of-market rents/value? Every rental property we stabilize or flip we undertake is rehabbed immediately to the highest quality (like A+++ condition, just-renovated home for sale), so we wouldn't ever think of dumping more money into it once it's built/renovated. Either our investment strategies are just completely different, or I am just missing something here.


    Separately, I concur on your thinking "it's more about improving my understanding of what COULD happen, not necessarily what WILL happen." Here's what is to the right of my MF hold model, I call it Risk Analysis, and it is auto-generated based on the metrics in the completed A&D model I previously replied with:

    This shows me how the deal will pan out should a variety of key-metrics change on me during the project (zoom in to right-side of image above, not the model I sent previously).

    Is this similar to what you are doing? This again is only useful to me at the point of purchase, to better visualize risks to the project while it is underway. For example, if I am about to offer $2M on one property projected to produce 10% CoC return, and $2M on another property projected to produce 10% CoC return, but HAD to choose 1, I would go with the more risk-adverse deal as indicated by these metrics.

  • Investor · Member since 2021 · 591 posts · 695 votes
    2y

    @Steven S. 

    I think that, for the purposes of discussion, the exact mechanics of the models are less important than the fundamentals of how and why people should use projection models. Yeah, your model will be different than mine, and yeah, you probably won't understand my models without looking at them and spending a lot of time learning to understand the inner workings of my models, my portfolio and my strategies. 

    Heck, it's taken me YEARS to refine my portfolio, models and strategies, and there have been plenty of times when even I wasn't completely sure which model was the best...there have even been instances when my model was producing projections I didn't understand (and I built the thing!). 

    If you were to look at a screen shot of one of my models, it wouldn't be clear what's occurring (partly because there are hidden layers with unseen variables and calculations that aren't visible on the top layer). Also, my models have plenty of weird quirks that I understand (because I built it), but which would be completely unintuitive to someone else... Not to mention my models are constantly changing. So, the exact mechanics of my models are not not something that can be easily conveyed in some screen shots on a forum post.

    Sure, I could show you a very simple model that anyone could understand at a glance (e.g.; rent is X today, it will increase at 2% per year, and will therefore by Y in year 5), but my real estate portfolio, strategies, and broader investment journey are a lot more complex than that, and so my models are more complex, and won't be easily understood by someone looking at a glance. 

    Likewise, I probably won't understand the inner workings and intricacies of someone else's model in just a couple minutes of looking at it on a forum post. 

    Like I mentioned, my first models were TERRIBLE (poorly designed, not particularly useful, didn't provide me with much insight), but I kept improving them over the years, and they became more and more useful. I didn't start out knowing exactly what the model should look like, or how it should function, because those things weren't entirely clear to me until I began building my models and molding them to my unique needs. Instead of starting by saying "my model should include variables A, B and C and calculations X Y and Z", I started by saying "Ok, my portfolio and finances currently looks like this...my goals are X, Y and Z, and I want to achieve those goals in X years...how do I model that out?"--and from there, the mechanics of the model evolved accordingly.

    If I had started by focusing on what the mechanics/variables/calculations should be, I wouldn't have gotten very far--it would have been like trying to design an airplane without first knowing what the purpose, context, acceptable limitations, performance requirements, etc. of the airplane were supposed to be...

    I'd encourage beginning investors to focus on discussing and learning the fundamentals of WHY and HOW to use projection models, and dive in and actually create and refine their own models with the goal of learning through doing. The more a person does, the more they'll learn, and the exact mechanics of the model will evolve according to their individual needs.

  • Investor · Hillsboro, OR · Member since 2016 · 304 posts · 153 votes
    2y

    I think if I started this I would be up all night.  

Join the conversationCreate a free account to reply, vote on answers and follow this thread.