Gator Lending? Why? 🐊
New to Real Estate · Austin, TX · Member since 2023 · 4 posts · 12 votes
Hey Everyone,
Newbie here trying to get some clarity on "gator" lending. I know, it's the flavor of the day, but it at least got me to to perk up. That said, I'm either missing something or this is another snake oil scheme. So the question is - why would someone entering a deal/assignment need a gator to cover EMD?
Let's say EMD is only between $2,000 and $5,000, depending on the deal. From my POV, it worries me that the person with this deal/assignment doesn't A. have $2k - $5k free for EMD OR B. Is willing to add another person (the gator) to this transition, further complicating it for only $2k - $5k + gator fee.
What am I missing here?
@Steven Greenwalt I don't not know exactly how Gator lending works. However from what I have read here, it seems like a really stupid idea. Borowing an EMD is super high risk and lending to someone who can't put come up with an EMD is also high risk. It seems like a really stupid concept to me.
Perhpas some with actuall knowledge of how it work could illuniate us. My guess is though that as you and I suspect it is the "flovor of the day" as you say and a pretty bad flavor at that.
I just saw a video of the gator guy saying he bought a property using Subject To with no money down. He used a gator lender to put in the money needed to finish the transaction. He said there was no equity in the property and yet he walked away with money at closing.
So, he buys a property that has no equity, uses an unsophisticated gator lender to overfund the deal, above the value of the property and he gets cash out.
For those of you in Rio Linda land, that means there is nothing protecting the gator lender. Nothing.
If he defaults, or the DOS is called or any number of others things, the gator lender has to either pay off the underlying loan that is taken Subject To, or lose their entire investment.
If the gator lender does pay off the underlying loan, they are stuck with about 10% costs to sell the property. So, an overleveraged property that had no equity to begin with and now an additonal loss from the costs of selling.
What could go wrong?
Now do you understand his version of "gator lending"?
@Steven Greenwalt I don't not know exactly how Gator lending works. However from what I have read here, it seems like a really stupid idea. Borowing an EMD is super high risk and lending to someone who can't put come up with an EMD is also high risk. It seems like a really stupid concept to me.
Perhpas some with actuall knowledge of how it work could illuniate us. My guess is though that as you and I suspect it is the "flovor of the day" as you say and a pretty bad flavor at that.
I just saw a video of the gator guy saying he bought a property using Subject To with no money down. He used a gator lender to put in the money needed to finish the transaction. He said there was no equity in the property and yet he walked away with money at closing.
So, he buys a property that has no equity, uses an unsophisticated gator lender to overfund the deal, above the value of the property and he gets cash out.
For those of you in Rio Linda land, that means there is nothing protecting the gator lender. Nothing.
If he defaults, or the DOS is called or any number of others things, the gator lender has to either pay off the underlying loan that is taken Subject To, or lose their entire investment.
If the gator lender does pay off the underlying loan, they are stuck with about 10% costs to sell the property. So, an overleveraged property that had no equity to begin with and now an additonal loss from the costs of selling.
What could go wrong?
Now do you understand his version of "gator lending"?
@Steven Greenwalt I don't not know exactly how Gator lending works. However from what I have read here, it seems like a really stupid idea. Borowing an EMD is super high risk and lending to someone who can't put come up with an EMD is also high risk. It seems like a really stupid concept to me.
Perhpas some with actuall knowledge of how it work could illuniate us. My guess is though that as you and I suspect it is the "flovor of the day" as you say and a pretty bad flavor at that.
I just saw a video of the gator guy saying he bought a property using Subject To with no money down. He used a gator lender to put in the money needed to finish the transaction. He said there was no equity in the property and yet he walked away with money at closing.
So, he buys a property that has no equity, uses an unsophisticated gator lender to overfund the deal, above the value of the property and he gets cash out.
For those of you in Rio Linda land, that means there is nothing protecting the gator lender. Nothing.
If he defaults, or the DOS is called or any number of others things, the gator lender has to either pay off the underlying loan that is taken Subject To, or lose their entire investment.
If the gator lender does pay off the underlying loan, they are stuck with about 10% costs to sell the property. So, an overleveraged property that had no equity to begin with and now an additonal loss from the costs of selling.
What could go wrong?
Now do you understand his version of "gator lending"?
Ahhh, I understand this version of "gator lending" now - thanks for clearing that up. As a matter of fact, I'm flying to Vegas now and will throw whatever money that I would've "gator lended" on the first table I see 😂
Because people are all told “you can get into real estate with no money!” Then they get something under contract, have a buyer all set up but no money! It’s better to have part of something than all of nothing. If you’re about to make $10+ thousand dollars and have no emd money, wouldn’t you have someone lend it to you for a fee then miss out on all of that money? Even if you give $5k to earn $10k wouldn’t that be worth it? To some people, it is!
@Steven Greenwalt I don't not know exactly how Gator lending works. However from what I have read here, it seems like a really stupid idea. Borowing an EMD is super high risk and lending to someone who can't put come up with an EMD is also high risk. It seems like a really stupid concept to me.
Perhpas some with actuall knowledge of how it work could illuniate us. My guess is though that as you and I suspect it is the "flovor of the day" as you say and a pretty bad flavor at that.
I just saw a video of the gator guy saying he bought a property using Subject To with no money down. He used a gator lender to put in the money needed to finish the transaction. He said there was no equity in the property and yet he walked away with money at closing.
So, he buys a property that has no equity, uses an unsophisticated gator lender to overfund the deal, above the value of the property and he gets cash out.
For those of you in Rio Linda land, that means there is nothing protecting the gator lender. Nothing.
If he defaults, or the DOS is called or any number of others things, the gator lender has to either pay off the underlying loan that is taken Subject To, or lose their entire investment.
If the gator lender does pay off the underlying loan, they are stuck with about 10% costs to sell the property. So, an overleveraged property that had no equity to begin with and now an additonal loss from the costs of selling.
What could go wrong?
Now do you understand his version of "gator lending"?
from what I have seen on the Facebook its a lot of beginner wholesalers daisy chaining deals. everyone is pleasant and lots of ra ra ra .
Two things I have seen, one form of Gator lending is indeed loaning money to wholesalers for EMD for a cut of the action.. either interest rate or profit whatever they can all negotiate.
The other is Gap funding loaning in the equity to make the purchase and securing it with a second as Mike alluded to, and again for an interest rate or an equity stake.. In the Pace Morby parlance I have come to learn that the gap funding or equity component is called and ET or "Entry Fee"..
There are a lot of folks on that facebook page meeting for the very first time.. and well that can lead to some folks being way to trusting.
This video below has the best explanation I've seen, even though the podcaster is still a fan boy. Skip to the 6:00 mark to get into the nitty-gritty. Pace has built multiple income streams that appear to be helping investors, but are really designed to make money for him. The more his students buy/sell, the more money Pace makes.
I believe the entire thing is a house of cards that will collapse when the market turns.

Because people are all told “you can get into real estate with no money!” Then they get something under contract, have a buyer all set up but no money! It’s better to have part of something than all of nothing. If you’re about to make $10+ thousand dollars and have no emd money, wouldn’t you have someone lend it to you for a fee then miss out on all of that money? Even if you give $5k to earn $10k wouldn’t that be worth it? To some people, it is!
Because people are all told “you can get into real estate with no money!” Then they get something under contract, have a buyer all set up but no money! It’s better to have part of something than all of nothing. If you’re about to make $10+ thousand dollars and have no emd money, wouldn’t you have someone lend it to you for a fee then miss out on all of that money? Even if you give $5k to earn $10k wouldn’t that be worth it? To some people, it is!
Well, in listening to "Mistakes to avoid when Gator lending (2023)" there are bigger worries to be concerned about than are spoken of in the "gator training". Apparently it doesn't always "get retuned'.
But hey, it's your money, do with it as you wish.
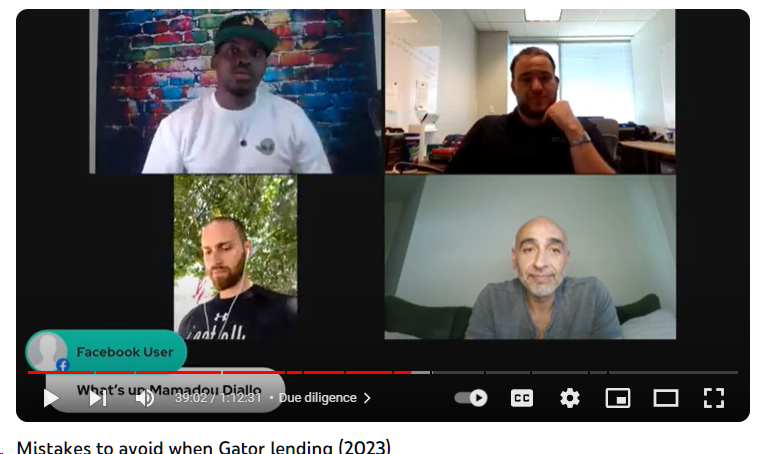
@Mike Hern
What do you mean your money isn’t returned?
I would have never suspected giving somebody who has no money and no experience to buy real estate would not get returned
Oh and your payday lending loan is also not secured
I remember when I used to drive by stores like this called payday loans and pawnshops - which atleast there you had to give up your Casio watch
@Chris Seveney: Your Question: "Apparently it doesn't always "get retuned'?"
You can see @Cheryl Vargas: @Desiree Alvarez: Discussion above to see how "gator lending" is sold to unsophisticated lenders.
According to the guys in the video, these loans can be as low as $1,000 for a non refundable emd. It costs $3,000 to join the group that pays back 150% of the amount borrowed for under 30 days. So, lend $10,000 for under 30 days and get $15,000 back. There is a contract that is signed.
These are "quick" transactions, within days, that the borrower (Subto student) needs "immediately" to provide a non refundable emd, for a Subto transaction.
Not much of a background check is done either on the transaction or on the borrower. No title report. And if someone needs to borrow $1,000 or $5,000 or $10,000 for a non refundable emd, what kind of security do you get?
If they have to borrow for an emd, they have no money to begin with. They likely have little in assets and nothing to secure the loan against. But, for lending $10,000 for a few days they pay $15,000 back after the 2nd gator lender provides longer term lending in 2nd position to complete the transaction with “no money out of the student’s pocket”. Pretty clever, eh? Like, what can go wrong?
If the Subto falls through and as you know many do fall through, how does the gator lender get paid back their $1000 - $5000 - $10,000 non refundable emd money they lent to the Subto student? They don’t. The borrower owes them money, but the borrower doesn’t have money to pay them back and the loan is unsecured. Kind of like a game of craps. Sometimes you win, sometimes you lose.
The guys in the picture above, are two sets of partners discussing how one guy borrowed money from both of them without any of them knowing he was borrowing from multiple people, then he ghosted them all.
They comment on how much work it was to track him down and prevent him from closing on a transaction unless they got paid back. It doesn’t appear it was his intention to pay them back anytime soon.
And in the example I gave about the overleveraged Subto that went bad, and the “Solution” was to sell to avoid a foreclosure on a Due on Sale, few if any of the Subto students can bring in $43,000 to closing, so it’s likely the property would go to foreclosure and the gator lender in 2nd position would lose most if not all of their money. Since the Subto student doesn’t have any money to pay the 2nd position gator lender, how do they get made whole? They don’t.
So, “Apparently it doesn't always "get retuned'!”
@Account Closed was being sarcastic.
"I would have never suspected giving somebody who has no money and no experience to buy real estate would not get returned"
Clearly Chris Knows giving money to such a person is stupid. Of course your breakdown is valueble for others reading along that don't yet get it.
@Mike Hern
What do you mean your money isn’t returned?
I would have never suspected giving somebody who has no money and no experience to buy real estate would not get returned
Oh and your payday lending loan is also not secured
I remember when I used to drive by stores like this called payday loans and pawnshops - which atleast there you had to give up your Casio watch
@Chris Seveney: Your Question: "Apparently it doesn't always "get retuned'?"
You can see @Cheryl Vargas: @Desiree Alvarez: Discussion above to see how "gator lending" is sold to unsophisticated lenders.
According to the guys in the video, these loans can be as low as $1,000 for a non refundable emd. It costs $3,000 to join the group that pays back 150% of the amount borrowed for under 30 days. So, lend $10,000 for under 30 days and get $15,000 back. There is a contract that is signed.
These are "quick" transactions, within days, that the borrower (Subto student) needs "immediately" to provide a non refundable emd, for a Subto transaction.
Not much of a background check is done either on the transaction or on the borrower. No title report. And if someone needs to borrow $1,000 or $5,000 or $10,000 for a non refundable emd, what kind of security do you get?
If they have to borrow for an emd, they have no money to begin with. They likely have little in assets and nothing to secure the loan against. But, for lending $10,000 for a few days they pay $15,000 back after the 2nd gator lender provides longer term lending in 2nd position to complete the transaction with “no money out of the student’s pocket”. Pretty clever, eh? Like, what can go wrong?
If the Subto falls through and as you know many do fall through, how does the gator lender get paid back their $1000 - $5000 - $10,000 non refundable emd money they lent to the Subto student? They don’t. The borrower owes them money, but the borrower doesn’t have money to pay them back and the loan is unsecured. Kind of like a game of craps. Sometimes you win, sometimes you lose.
The guys in the picture above, are two sets of partners discussing how one guy borrowed money from both of them without any of them knowing he was borrowing from multiple people, then he ghosted them all.
They comment on how much work it was to track him down and prevent him from closing on a transaction unless they got paid back. It doesn’t appear it was his intention to pay them back anytime soon.
And in the example I gave about the overleveraged Subto that went bad, and the “Solution” was to sell to avoid a foreclosure on a Due on Sale, few if any of the Subto students can bring in $43,000 to closing, so it’s likely the property would go to foreclosure and the gator lender in 2nd position would lose most if not all of their money. Since the Subto student doesn’t have any money to pay the 2nd position gator lender, how do they get made whole? They don’t.
So, “Apparently it doesn't always "get retuned'!”
Sorry Mike I was being 100% sarcastic on my post and was kidding.
I would be more surprised if the money was actually returned.
you're not missing anything; i have the same worry about gator lending. however, sometimes people are looking for way larger amounts of transactional lending, for bigger deals. in those cases, it's more justified for them to need the $ IMO. but also, more is on the line, so you still have to really do your due diligence. if you're really interested in being a gator, take pace's program. i haven't, but if i was going to seriously get into it, i would.
@Account Closed I think @Chris Seveney was being sarcastic.
"I would have never suspected giving somebody who has no money and no experience to buy real estate would not get returned"
Clearly Chris Knows giviing money to such a person is stupid. Of course your breakdown is valueble for other ereading along that don't yet get it.
@Ned Carey: Your comment: "Perhpas some with actuall knowledge of how it work could illuniate us." and @Chris Seveney was willing to set up the scenario so I could respond.
So, I took the time to find out. ;-)
Lol. Yes, I know @Chris Seveney already knew that and was having fun. As I've mentioned in the past, I write for the "lurkers". Most people never post, but they do read and I welcome the opportunity to provide a little insight as to why being this "gator lender" stuff is very bad advice.
"You can see @Cheryl Vargas: @Desiree Alvarez: Discussion above to see how "gator lending" is sold to unsophisticated lenders."
I'd be surprised if the way they are teaching & doing the lending is legal. (they say it is a "fund of funds" and stuff like that)
It gets worse, but that's for another post.
There’s a funny Key and Peele comedy sketch called “ You can’t con a con artist when you’re also a con artist” where two scammers try to scam each other without realizing the other is a scammer. That’s what this reminds me of. “You give me the 20, I’ll give you the 3, then I’ll give you the 17 later and to let you know that I’m legit I’ll let you hold on to my Yogurtland punchcard with 7 punches on it in the meantime. You can’t fake that.” Lol.
you're not missing anything; i have the same worry about gator lending. however, sometimes people are looking for way larger amounts of transactional lending, for bigger deals. in those cases, it's more justified for them to need the $ IMO. but also, more is on the line, so you still have to really do your due diligence. if you're really interested in being a gator, take pace's program. i haven't, but if i was going to seriously get into it, i would.
Why would anyone seriously get into? And who ever would?
The fact this type of topic exists is mind blowing. It's like a ponzi scheme but you're involving an adult that literally has no cash or asset to his or her name.
lol.. i am reading all your posts and you clearly are the experts(i say sarcastically!) .I am a gator and i can tell you that the process works. Just like any real estate investing, there is always risks but we are well trained in the community on how to ensure we are protected (including the right paperwork). The people in his communities are making the money through partnering and connecting on all types of transactions where everyone can win. So, dont you worry about us gators... we are doing just fine.. But, still.. If you think Grant Cardone would do business with a scammer then I guess i am in good company! cheers to 2024!
lol.. i am reading all your posts and you clearly are the experts(i say sarcastically!) .I am a gator and i can tell you that the process works. Just like any real estate investing, there is always risks but we are well trained in the community on how to ensure we are protected (including the right paperwork). The people in his communities are making the money through partnering and connecting on all types of transactions where everyone can win. So, dont you worry about us gators... we are doing just fine.. But, still.. If you think Grant Cardone would do business with a scammer then I guess i am in good company! cheers to 2024!
Hey Steven!
The idea behind gator lending is to help wholesalers scale their business. If a wholesaler is doing 5 deals per month with 5k EMD for each deal, that is 25k out of pocket and may limit the amount of deals that wholesaler can do. With the help of a gator lender, that wholesaler does not have to worry about that and can do as many deals as they want creating a win-win situation for both the wholesaler and gator.
Happy to chat more as well.
The PRIMARY reason this was created was for another great revenue stream for Pace Morby. Secondary would be for all of the clients, "Gators" who follow his program and use it.
MAJORITY of the clients don't even have a little capital, enough to fund the first EMD deal and come back to the group for funding. In the program they can bring their deals back to the program and allow "Pace" to fund while keeping the bulk of the profit leaving a little for the "gator". Meanwhile, Paces clients very slowly build up their capital, but we all know the majority will spend it and come right back to the group to let Paces organization fund it so he continues building his wealth from all of these "gators".
Do I get annoyed hearing about this every day..YES..Do I think it was a great form of revenue for Pace..YES. Do I feel that over 80% never will do a deal and or don't know what the F they are doing..YES which makes it even more annoying. However, those few who are financially saavy and have integrity and grit I believe will benefit from it until they are able to have enough experience to go off and do their own thing, charge less fees and be able to have more repeat business while keeping a much higher ROI themselves.
And NO, i've never been in this program, been around much longer than he even thought of this revenue stream. But I do refer any EMD request over to a contact of mine who happens to be one of those 20%. He's used the program to learn but wise enough to realize his own potential and live within his means while stepping away from his W2 and becoming an entrepreneur. I'm all for seeing others get away from the rat race and have the grit to fight and create their own success story.
Hey Steven!
The idea behind gator lending is to help wholesalers scale their business. If a wholesaler is doing 5 deals per month with 5k EMD for each deal, that is 25k out of pocket and may limit the amount of deals that wholesaler can do. With the help of a gator lender, that wholesaler does not have to worry about that and can do as many deals as they want creating a win-win situation for both the wholesaler and gator.
Happy to chat more as well.
I think it’s disingenuous for a guru to claim they created a new method that is “revolutionizing” real estate lending, when it’s actually just rebranding something that exists and charging more for it. Suckers are born every day. Everybody else just calls “Gator Lending” Transactional Funding, it’s not something new. My lender provides this without an $8k fee to join a Facebook group.
i debated to reply but i will only add a few comments to those that are considering themselves as "experts" on what PACE is teaching... Reality is : no, PACE is not saying he is creating something new with gator. Even with SUbto, he openly states these are lending options that have been around for a long time. What differentiates his approach: 1) EMD is just one of the gator options. if you are not part of his community, you dont see the rest of the options and training of others lending/JV options to make money. it goes so much further than just EMD to make money 2) he is a great teacher on the concepts and builds his community of go-givers working together. He is open in his training about risks and teaching realities of real estate. he is not fluff in his comments nor critical feedback. he breaks the training down for newer investors so it makes sense and constantly is sharing what is required to help protect yourself 3) the community he has built =instant lead generation for people to work together to get deals closed!. isnt that the goal??? The vibe in the community is FIRE.. people working with people to partner , gaing profit and grow.4). If you are growing your business to be a million dollar business, it is highly unlikely you are doing that without OPM. Pace provides access to OPM to get started and grow your network and teaches and proiveds access to Rasing private capital to allow you to close more deals as you get your network built.
Reality: In the beginning, most people need help to start growing their funds. he enables this through his network, teaching and creative options to access OPM. So to say you wont lead money to someone that doesn't have the EMD, you are thinking with a limited mindset. If a wholeseller is really thriving, they need access to OPM. that is why there are thousands of transactional lending groups because the demand is there. and with regulations changing, this will become more relevant. bottom line: pick what you think if best for where you are at on your real estate investment journey. If you are well experienced and have networks and leads, PACE might not be the right fit for you. If you are newer and looking to find a safe place to learn and grow, he offers a great community of leaders wanting to help others. And to target PACE for making money through his community is insane. he gives so much to his community and i would challenge you to find anyone in his community that say they are not getting their value. I spent 20K for a mentorship that hasnt given me a fraction of what i am gaining from being in the gator community. So, lets try not to hate on what you dont understand. we are all here to learn and connect and build our networks and build our financial freedom and keep more of our hard earned money!!! cheers
Hey Everyone,
Newbie here trying to get some clarity on "gator" lending. I know, it's the flavor of the day, but it at least got me to to perk up. That said, I'm either missing something or this is another snake oil scheme. So the question is - why would someone entering a deal/assignment need a gator to cover EMD?
Let's say EMD is only between $2,000 and $5,000, depending on the deal. From my POV, it worries me that the person with this deal/assignment doesn't A. have $2k - $5k free for EMD OR B. Is willing to add another person (the gator) to this transition, further complicating it for only $2k - $5k + gator fee.
What am I missing here?
think bigger.. a wholeseller could have many deals and not EMD for all. so they need OPM to help secure. its not just about that one deal.. Goal is volume, right? so if you want more volume you need OPM. especially if you're doing a double close. given up some of the profit on one deal too close multiple deals is a better decision for the wholeseller.
