Transferring Title w/ Mortgage

Transferring Title w/ Mortgage

Member since 2021 · 3 posts · 0 votes

Hello, 

I purchased a home in Michigan and am entertaining sectioning off the lower level as it's own apartment, and renting it out to a tenant below. It has its own kitchen, bathroom, etc. I would be living on the upper level "unit", and renting out the lower level "unit", but it would still be zoned as single family. 

I've gotten mixed feedback, but how do I go about title on this? I would love to have title under an LLC, but my lender is explaining that because it is my primary residence, the lender could technically call the loan if I am using it as a rental property.


I am looking to purchase another property in the near future, but a similar question remains. To close, I am being told I would need to have the property titled under my name. How do I go about transferring the title over to an LLC after closing, without complicating the mortgage? I'm a new investor, so sorry if this has been asked countless times before.


Hoping there are some other Michiganders here that can help! 


Thanks
0Reply
20 views

4 Replies

Jump to latestLatest
  • Lender · Winlock, WA · Member since 2013 · 1k+ posts · 1k+ votes
    4y

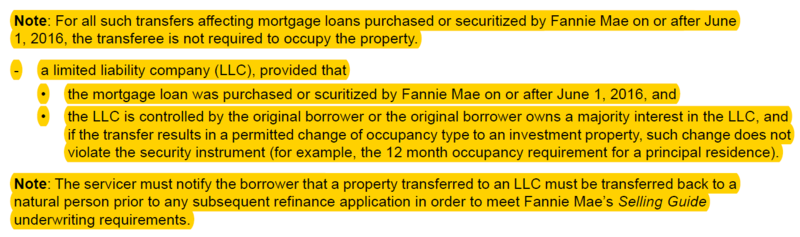
    If you currently have a Fannie Mae loan on this property, Fannie changed the rules back in June 1 2016 which allows the borrowers on the loan to transfer title to an LLC that they are the majority members of, without it violating the Due on Sale clause. They did this because they saw that many investors were doing this, so they made the change so it doesn't hurt someone doing this. We anticipated that Freddie Mac would have followed Fannies lead, but to my knowledge Freddie didn't?

    So go look at your mortgage and see if it is a Fannie Mae loan. If so, proceed to transfer without any worries. If it is not, then you are taking the chance that the lender can call the mortgage due. The fact that you made your primary residence into a primary with a rental, will not cause any issues with your lender.

    The future purchase, just assure that your lender only gives you a Fannie Mae loan. Then after closing, go ahead and transfer it without fear of the Due on Sale clause.

  • Morris County, NJ · Member since 2020 · 5k+ posts · 2k+ votes
    4y

    @Evan Vallis

    So, this comes up many times.  The Due on Sale clause I hear is rarely called in.  Honestly, it really shouldn't be much of an issue --- if its called in, just refinance...

    I hope you realize that legal entities, such as a LLC, are not eligible for conforming residential loans. this is why you are looking into potentially "frankensteining" your properties. Consult some professionals, but I keep writing about this and nobody seems to refute. If the mortgage is under your name but Title is under the LLC's, whose bank account from which do you draft the mortgage payments? Technically, which entity (aside from being disregarded if its single member) takes the deduction? I just see it as messing with your LLC's corporate veil, especially if you do this multiple times. Now, the LLC isn't standing on its own.

    If you really want to do it "cleanly," just get a commercial loan (i.e. any sort of "non-residential" loan which people seem to come up with many different names for the various loan products) and reTitle to your LLC. When you purchase, take Title directly into your LLC and use a commercial loan again. I know most people don't want to hear this because they don't want the cost/expense of the commercial loan, but if you seriously want the limited liabiilty of the LLC, you really do/should have to pay for it. Otherwise, just do what many other investors do and hold Title in their personal name, keep the property in good repair, and have insurance including an Umbrella policy.

    Hope this helps.  Good luck.

    As always, consult some professionals..

  • Member since 2021 · 3 posts · 0 votes
    4y

    Thank you all for your replies! This information is very much appreciated. Happy Thanksgiving! 

  • Drew SygitBusiness Member
    Property Manager · Royal Oak, MI · Member since 2012 · 12k+ posts · 9k+ votes
    4y

    Commercial mortgages/loans typically have lower interest rates and are 5 year balloons. 

    That's why everyone wants to use conforming mortgages - with their lower rates and 30 year fixed terms.

    He who has the gold, makes the rules - so you have to follow FNMA"s rules if you want their mortgages.

Join the conversationCreate a free account to reply, vote on answers and follow this thread.